Flood insurance in San Antonio: why your homeowners policy stops at the front door
Flash flooding is the costliest weather risk most Texas homeowners are not insured for. Here is how flood coverage works.
 Daniela FuentesPersonal lines agent · May 20, 2026 · 7 min read
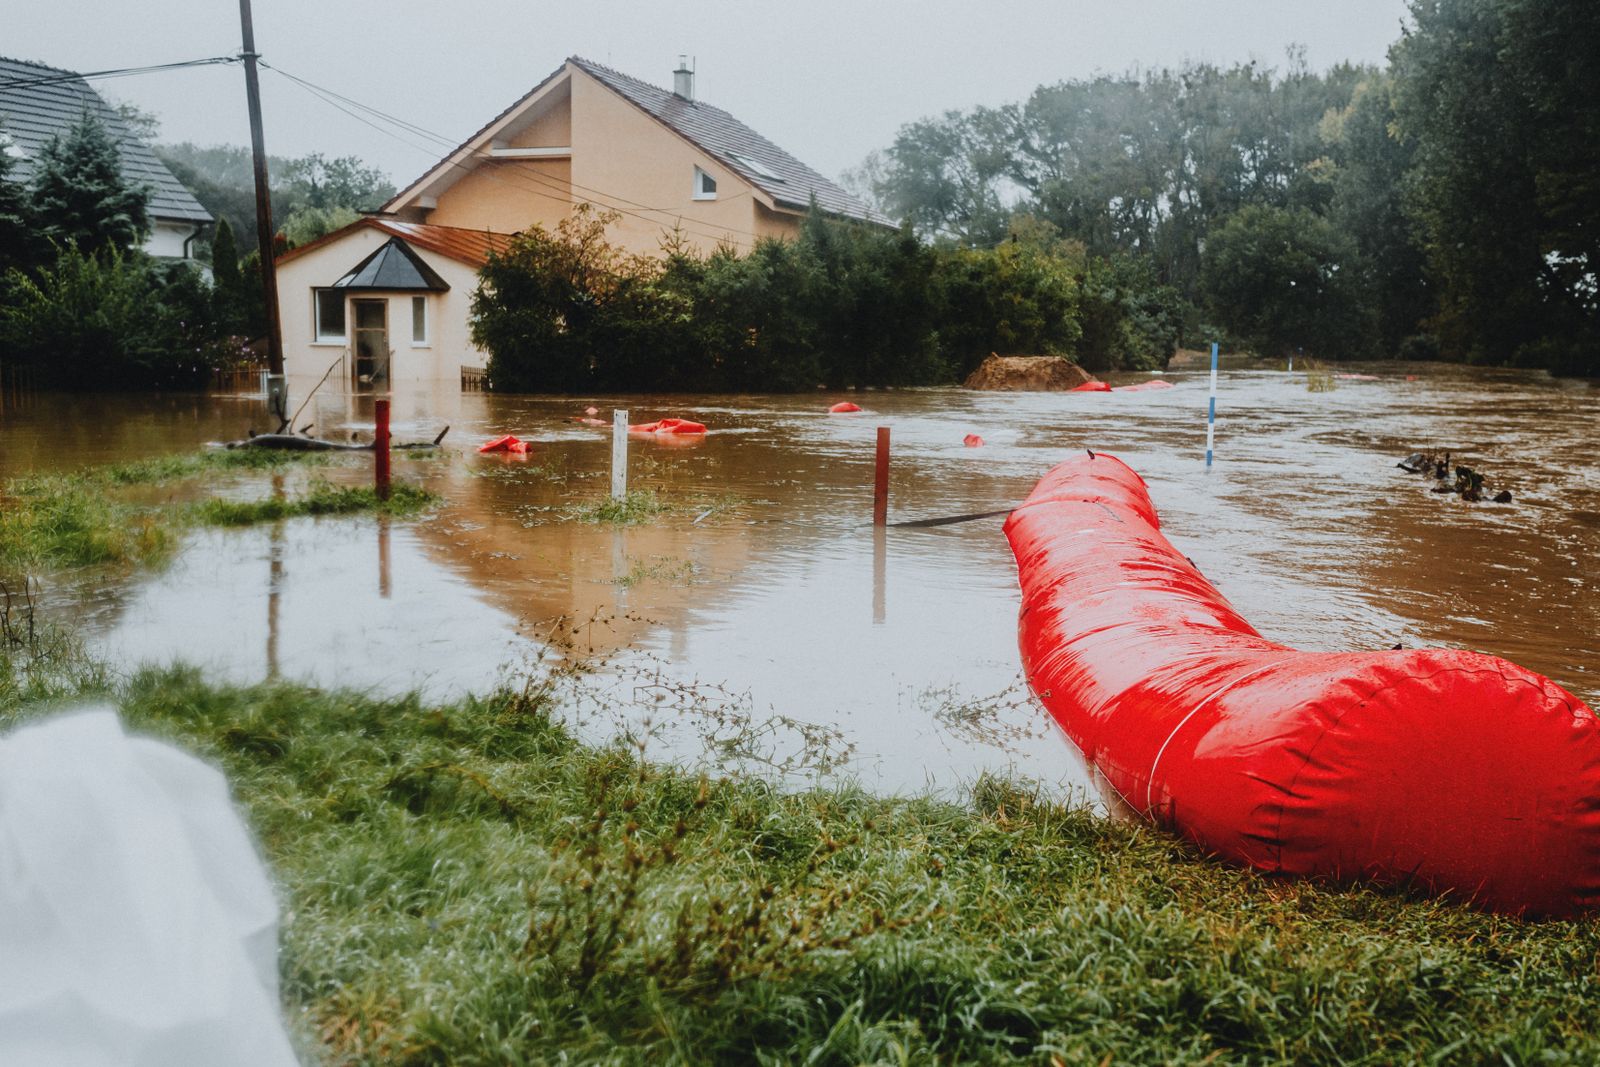
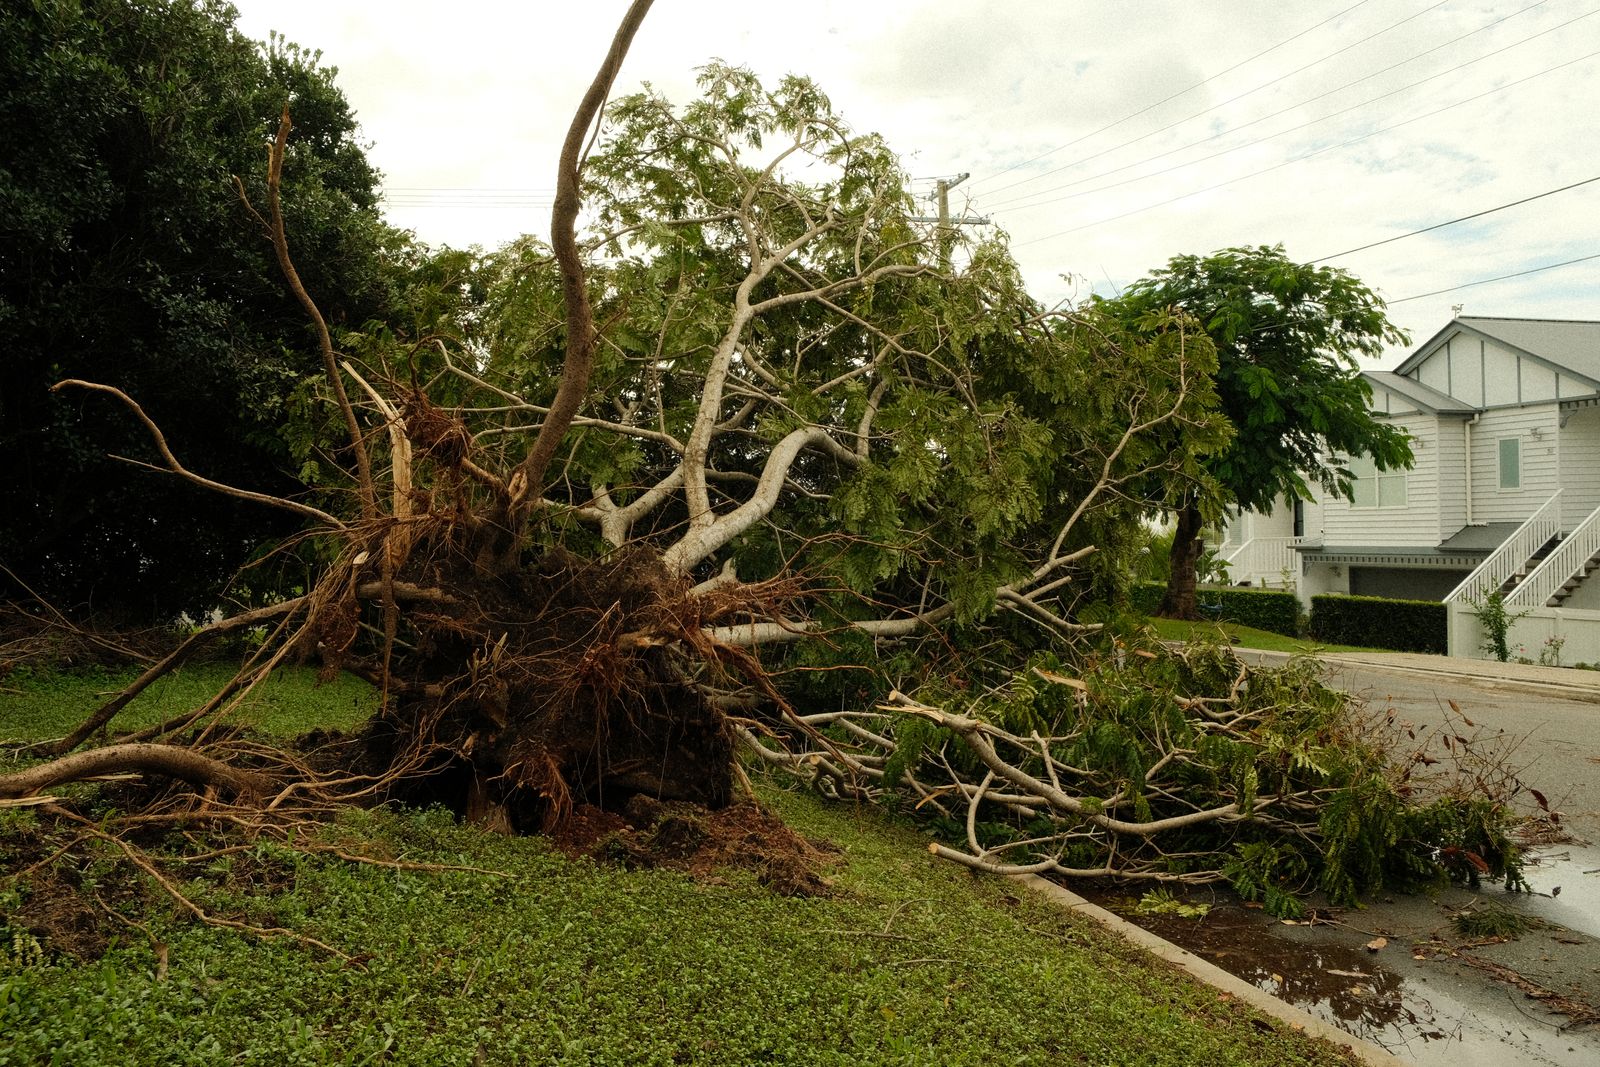
San Antonio sits in one of the most flash-flood-prone regions in the country. Heavy Hill Country rain moves quickly down creeks like Salado, Leon and Olmos, and low-water crossings can turn dangerous in minutes. Yet most homeowners we meet assume their homeowners policy covers flood. It does not.
What homeowners insurance covers, and what it excludes
A standard Texas homeowners policy covers sudden water damage from inside the home, like a burst supply line, and often rain that enters through a storm-damaged roof. Water that rises from the ground or overflows from a creek, river or street is classified as flood and excluded.
That distinction matters. Two inches of floodwater across a 2,000-square-foot home can require new flooring, drywall, baseboards and cabinets, easily costing tens of thousands of dollars.
Your two main options
The National Flood Insurance Program, managed by FEMA, offers up to $250,000 for the building and $100,000 for contents. Private flood carriers can offer higher limits, loss of use coverage and sometimes lower prices for homes outside high-risk zones.
- NFIP: standardized coverage, required by many lenders in high-risk zones, 30-day waiting period.
- Private flood: flexible limits and features, underwriting varies, waiting periods vary by carrier.
- Excess flood: adds building coverage above NFIP limits for higher-value homes.
Do you need flood insurance outside a high-risk zone?
Flood maps show relative risk, not a guarantee. A meaningful share of flood claims nationwide come from properties outside high-risk zones, and preferred-risk policies in lower-risk areas are often surprisingly affordable. In a sample quote for a Northwest Side home in zone X, building and contents coverage came to roughly $38 a month.
Timing: buy before the forecast
Most NFIP policies have a 30-day waiting period before coverage starts, with limited exceptions such as a new mortgage. That means you cannot wait for a tropical system to appear in the Gulf. Spring, before storm season, is the ideal time to add flood coverage.
Make a flood plan for your household
- Take a video walkthrough of your home and belongings and store it in the cloud.
- Keep important documents in a waterproof container on an upper shelf.
- Know your nearest low-water crossings and never drive through moving water.
- Save your carrier's claim line and your policy number in your phone.
Let us check your address
Send us your address and we will look up your flood zone, compare NFIP and private flood options and explain how flood coverage fits with your homeowners policy. It takes about 15 minutes and there is no obligation. Premium examples in this article are sample figures, and coverage is subject to the terms of each flood policy.
This article is general information, not legal or coverage advice. Your policy terms, conditions and exclusions determine coverage.