Home insurance in San Antonio
Hail, wind and a roof that has seen a few Texas summers. We match your house with a carrier that treats it fairly.
How we approach home coverage
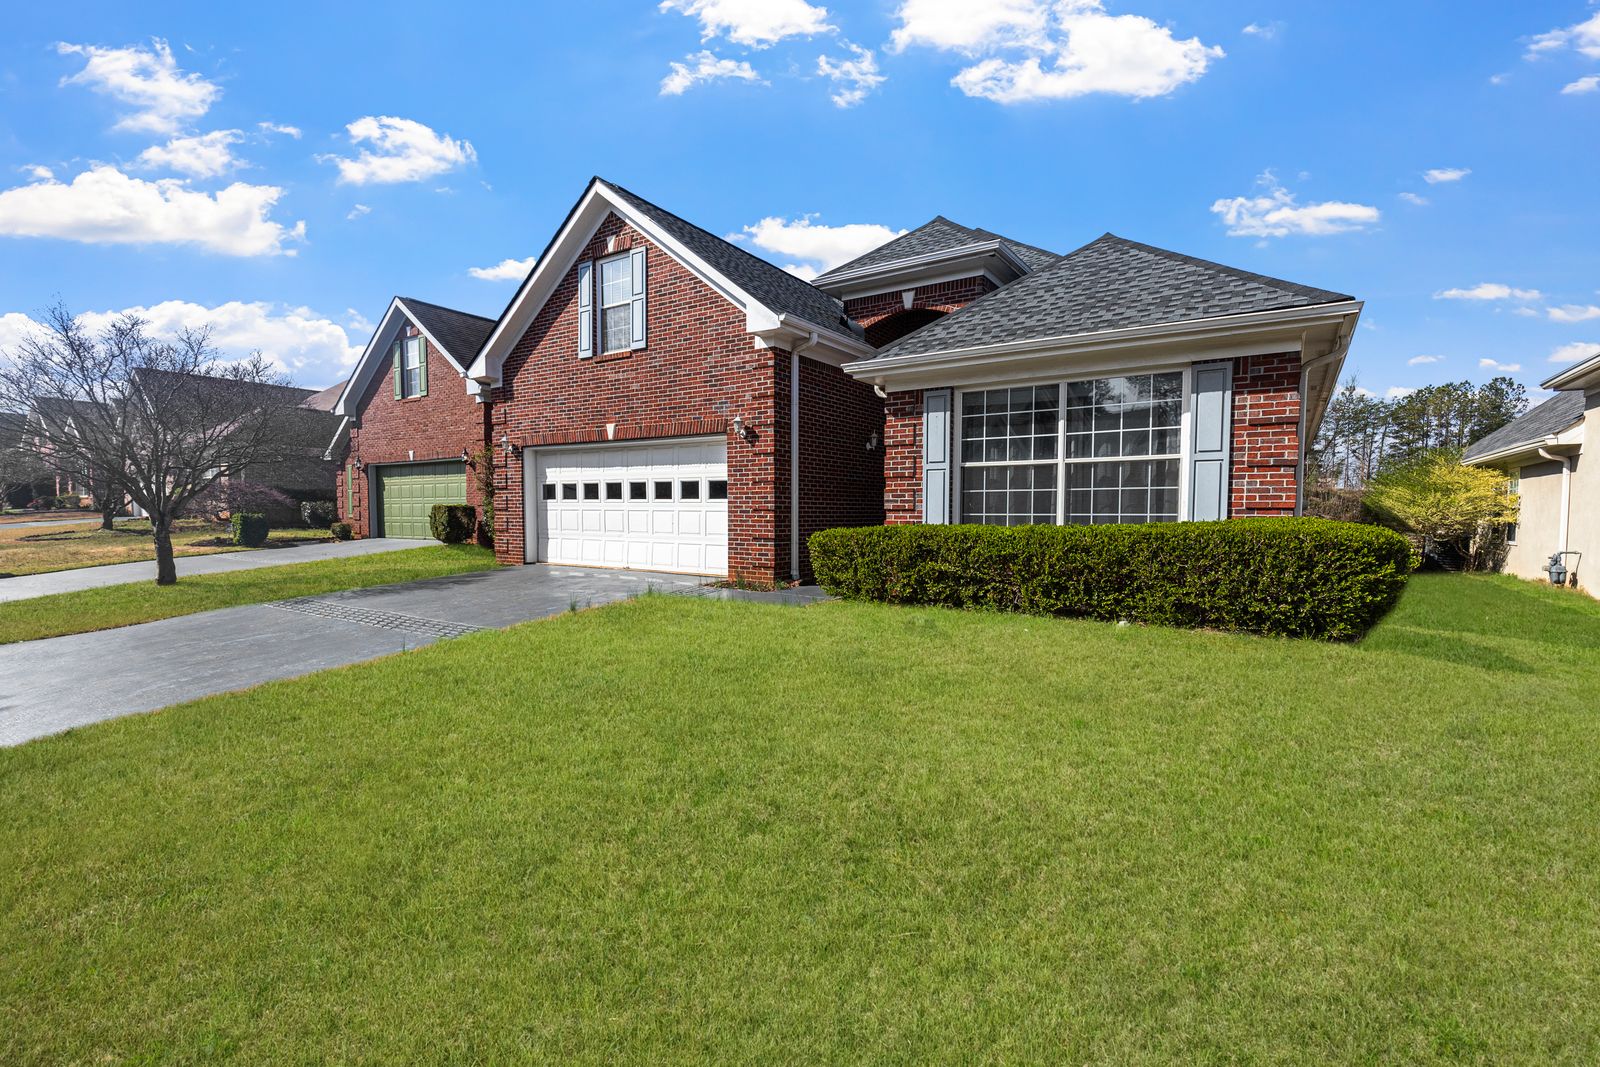
In Bexar and Comal counties the biggest homeowners question is usually not price, it is the roof. Many carriers now use percentage wind and hail deductibles or pay older roofs at actual cash value. We read those details for you before you sign.
We check replacement cost against today's building prices, add water backup and foundation options where they make sense, and tell you clearly what a standard policy does not include, like flood.
- Roof and hail deductible review
- Mortgage company paperwork handled for you
- Claims advocacy after storms
- Bundle discounts with auto
What's included
Core protections and the options our agents most often recommend. Exact coverage depends on the carrier and your policy terms.
Dwelling coverage
Rebuilds your home after a covered loss, based on current construction costs in the San Antonio market.
Other structures
Fences, detached garages, sheds and pergolas, commonly 10% of the dwelling limit.
Personal property
Furniture, electronics and clothing, with replacement cost options instead of depreciated value.
Loss of use
Hotel, rental and extra meal costs while your home is being repaired.
Personal liability
Protection if a guest is hurt at your home or your dog bites a neighbor.
Optional endorsements
Water backup, foundation water damage, scheduled jewelry and home business add-ons.
How getting covered works
- 1
Share your address and roof age
We pull public property data and ask a few questions about updates.
- 2
Estimate replacement cost
We check your dwelling limit against local rebuild costs, not market value.
- 3
Compare deductibles
See flat versus percentage wind and hail deductibles in real dollars.
- 4
Bind and send to your lender
We send the declarations page and invoice to your mortgage company.
What affects your price
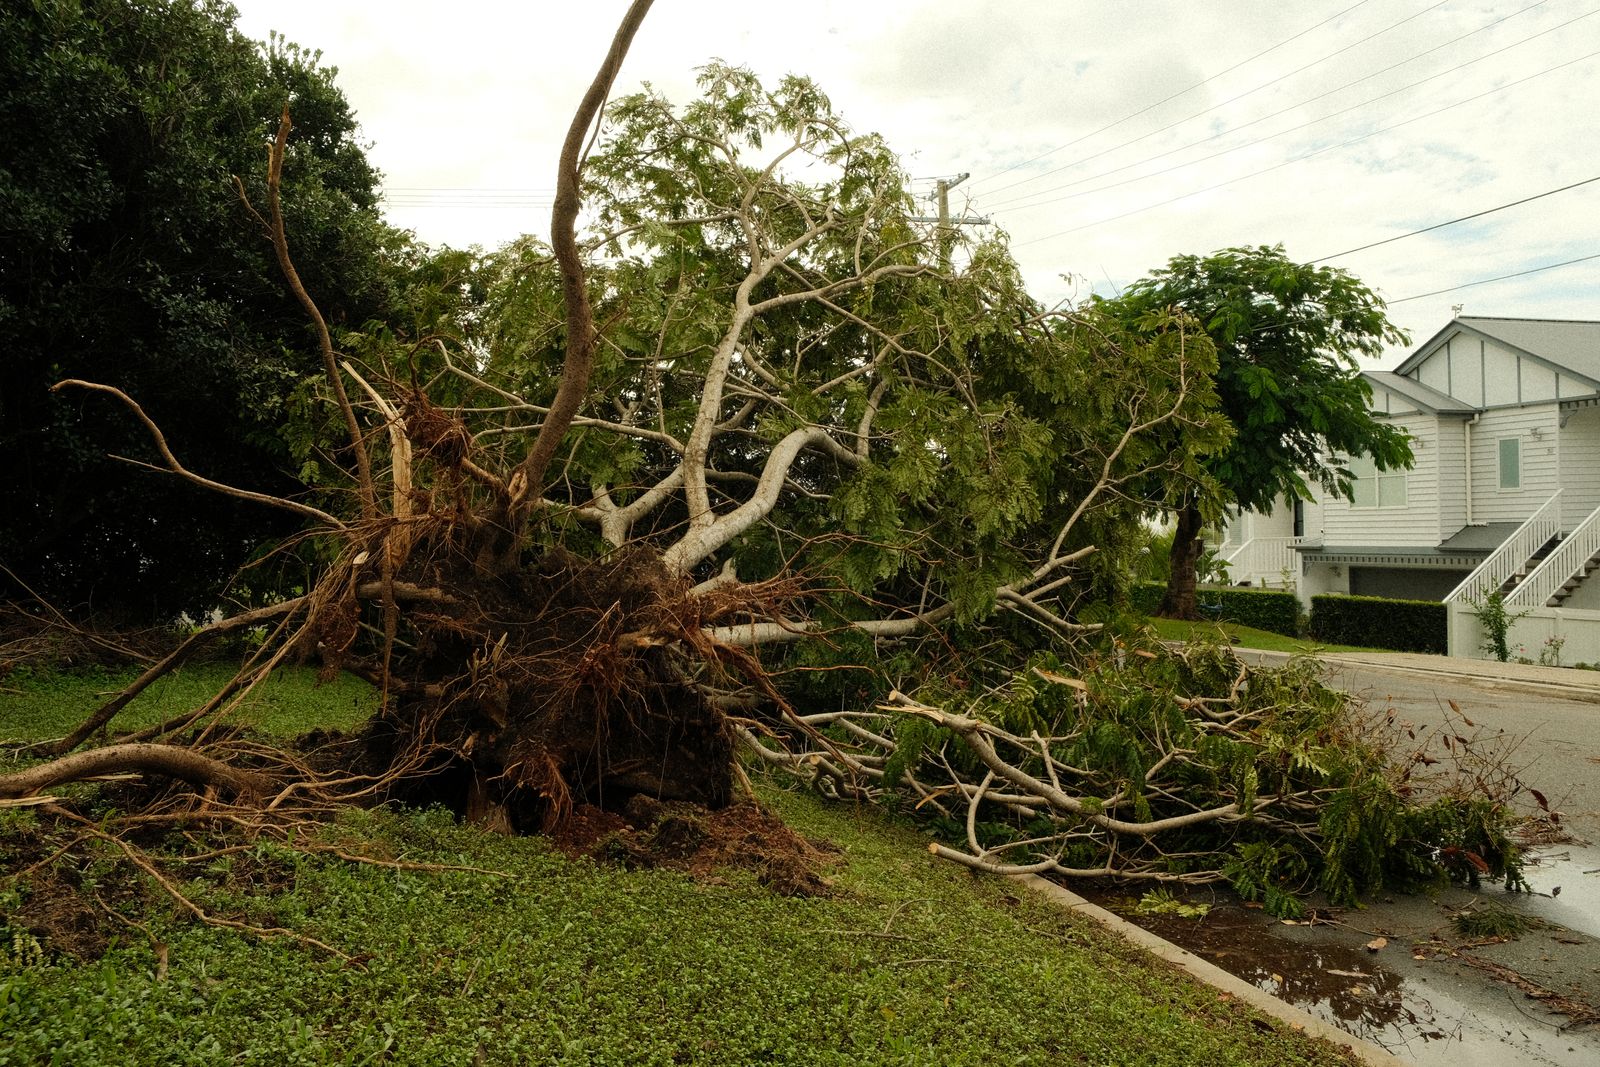
Carriers weigh these factors differently, which is exactly why comparing several of them pays off.
- Roof age and material
- Impact-resistant Class 4 shingles can earn credits; roofs over 15 years may limit options.
- Location
- Distance to a fire station, hail history and wind exposure in your ZIP code.
- Rebuild cost
- Square footage, construction type and finishes set the dwelling limit.
- Claims history
- Prior claims at the property or by the owner in the last 5 years.
- Deductible choice
- A 2% wind and hail deductible lowers premium but raises out-of-pocket risk.
Home insurance questions
More answers on our FAQ page.
No. Standard Texas homeowners policies exclude flood from rising water. Flood coverage is a separate policy through the NFIP or a private carrier, usually with a 30-day waiting period.
Instead of a flat $1,000, the deductible is a percent of your dwelling limit. On a $350,000 home a 2% deductible is $7,000. We show you the dollar amount before you choose.
It depends on the damage and on whether your policy pays roofs at replacement cost or actual cash value. We explain that setting when you buy and help you document damage after a storm.
Settling and cracks from soil movement are usually excluded. Some carriers offer an endorsement for foundation damage caused by a plumbing leak, which is common in San Antonio clay soils.
Often paired with home
Auto insurance
Liability, full coverage, uninsured motorist and roadside help, shopped across 20+ carriers.
View coverage
Umbrella insurance
Extra liability protection above your auto and home limits, from $1 million.
View coverage
Condo insurance
Walls-in coverage, loss assessment and liability built around your HOA master policy.
View coverageCompare home quotes today
Real agents in San Antonio, answers in English or Spanish, and no obligation to switch.
4.9 average from 1,284 client reviews