“After the April hailstorm, Daniela walked me through the claim and caught that my roof was paid at actual cash value. We fixed that at renewal. Real advice, not a sales pitch.”
Marisol TreviñoAlamo Heights · Home + auto bundle
Open today
Mon-Fri 8:30-6 · Sat 9-1 · Hablamos español
Independent agency · San Antonio since 2004
We compare 20+ carriers for auto, home and business insurance. Bilingual agents, local claims help and one free quote.
Nine lines of coverage, each quoted with several carriers and explained without jargon. Bundle two or more and most households save.
Need an SR-22? We file with Texas DPS, usually the same day.
Liability, full coverage, uninsured motorist and roadside help, shopped across 20+ carriers.
Dwelling, belongings and liability, with roof, hail and wind deductibles explained plainly.
Belongings, liability and temporary housing for apartments, duplexes and rental homes.
Walls-in coverage, loss assessment and liability built around your HOA master policy.
Term, whole and final expense life insurance with plain-language needs analysis.
Extra liability protection above your auto and home limits, from $1 million.
Property, general liability and business income combined for small businesses.
Liability and physical damage for vehicles used for work, from one truck to a small fleet.
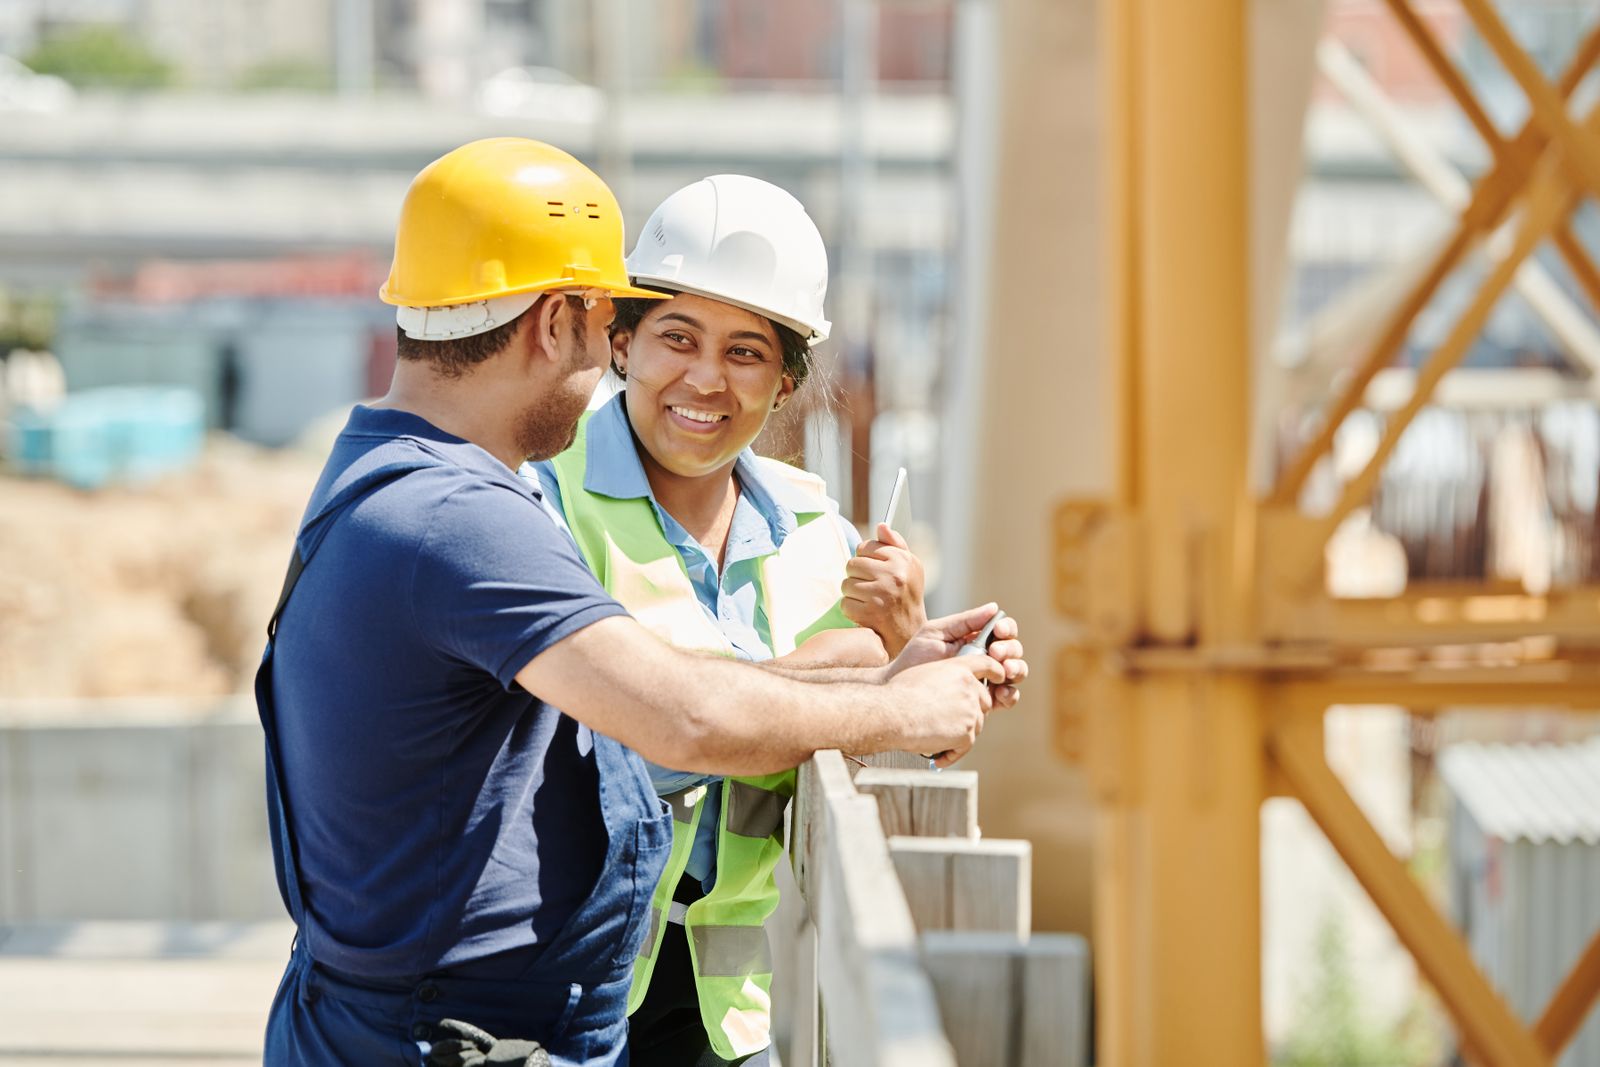
Workers' compensation and nonsubscriber options for Texas employers with 1 to 100 employees.
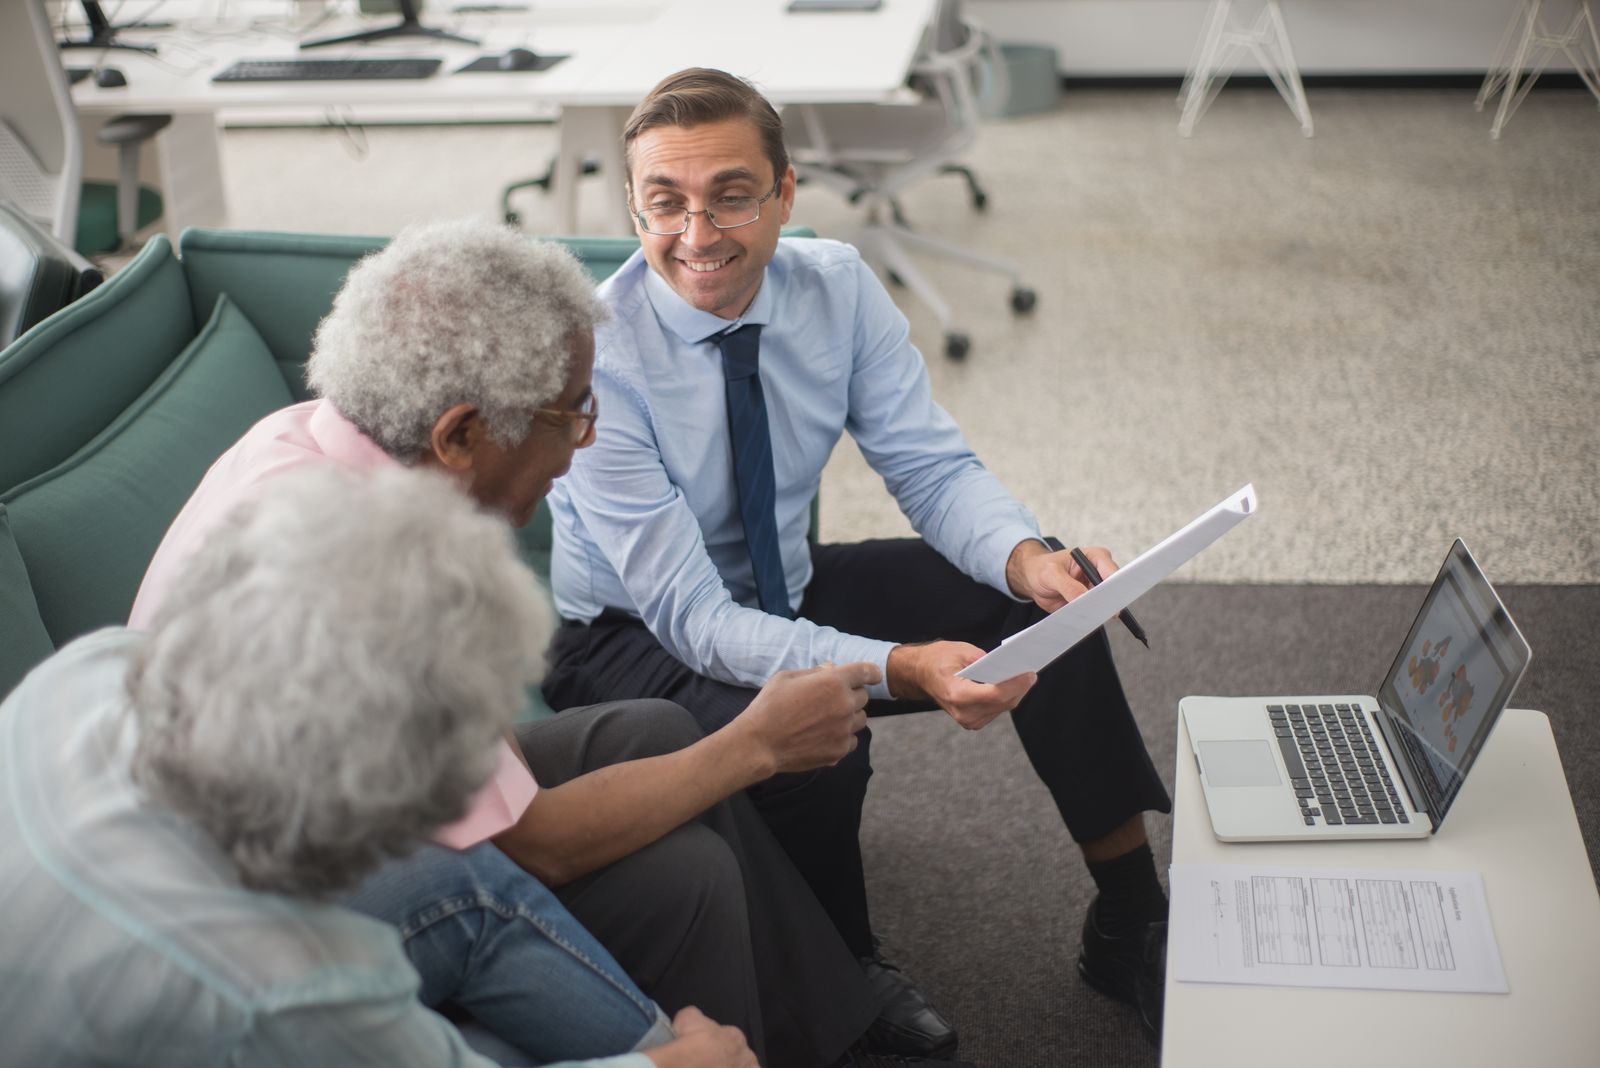
Twenty minutes at our office, on the phone or over video. You leave with a written summary, whether you switch or not.
We started this agency so our neighbors would have someone who picks up, explains the fine print and pushes for the claim.
From a first lease to a third work truck, our clients look a lot like San Antonio: family-run, bilingual and busy.
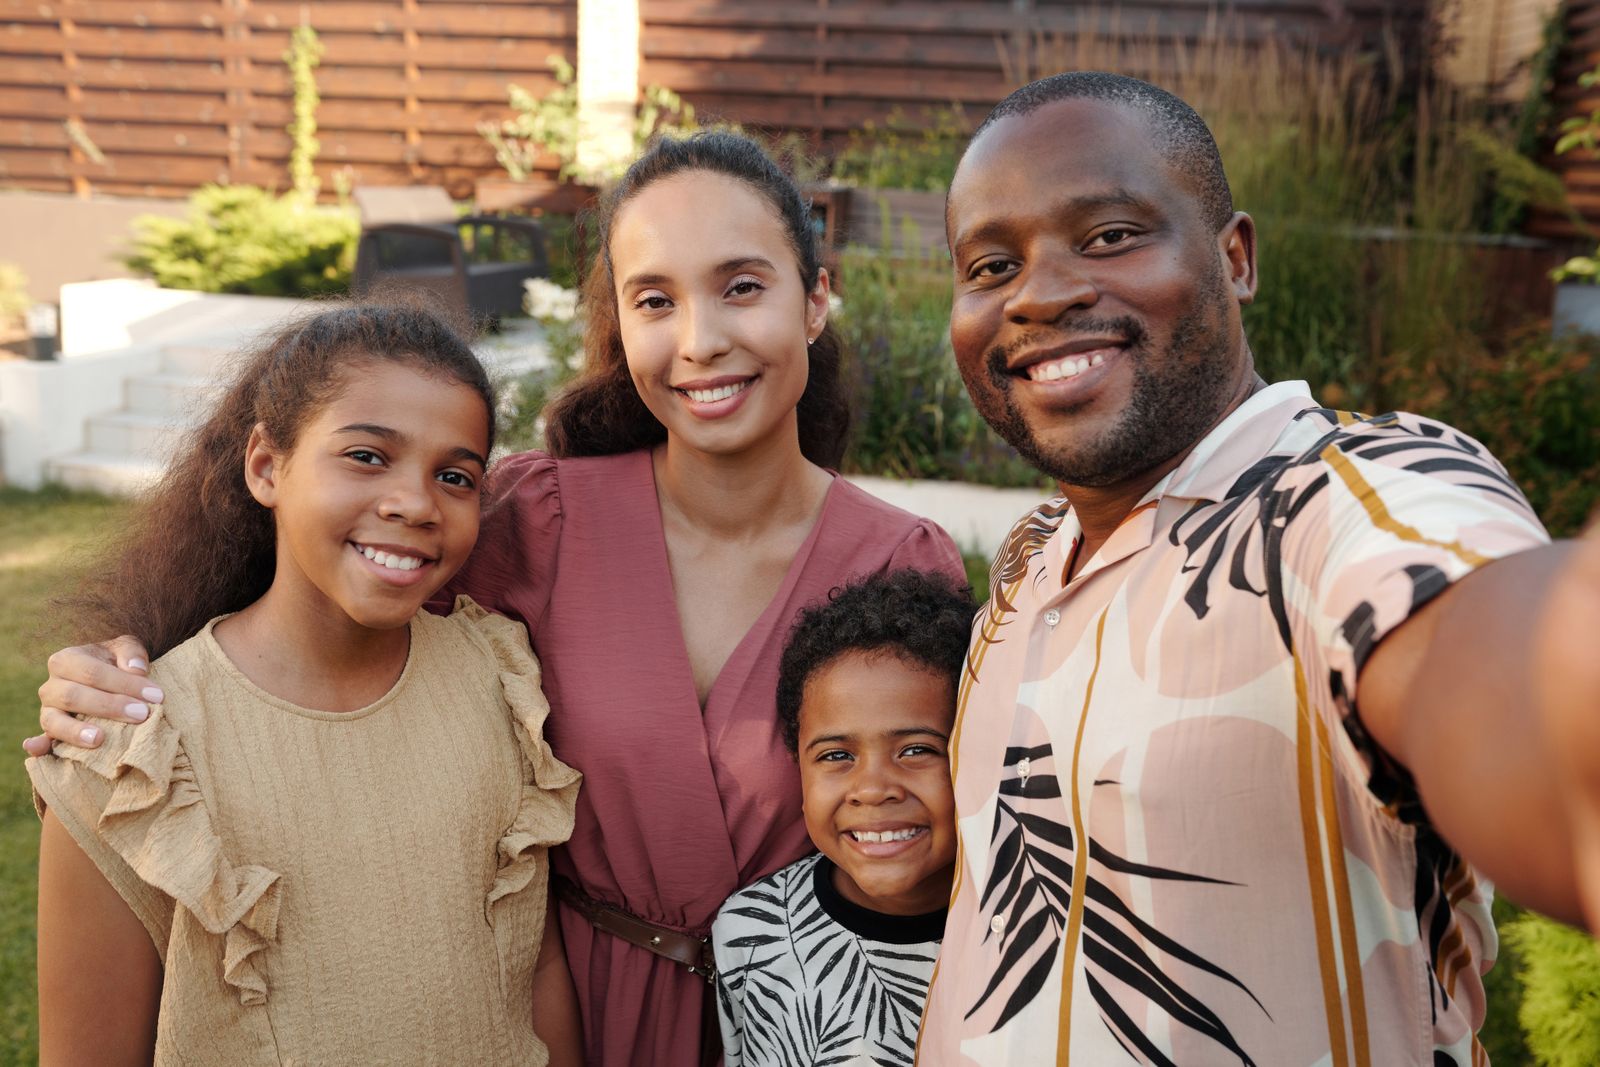 Families in Westover HillsHome, two autos and term life
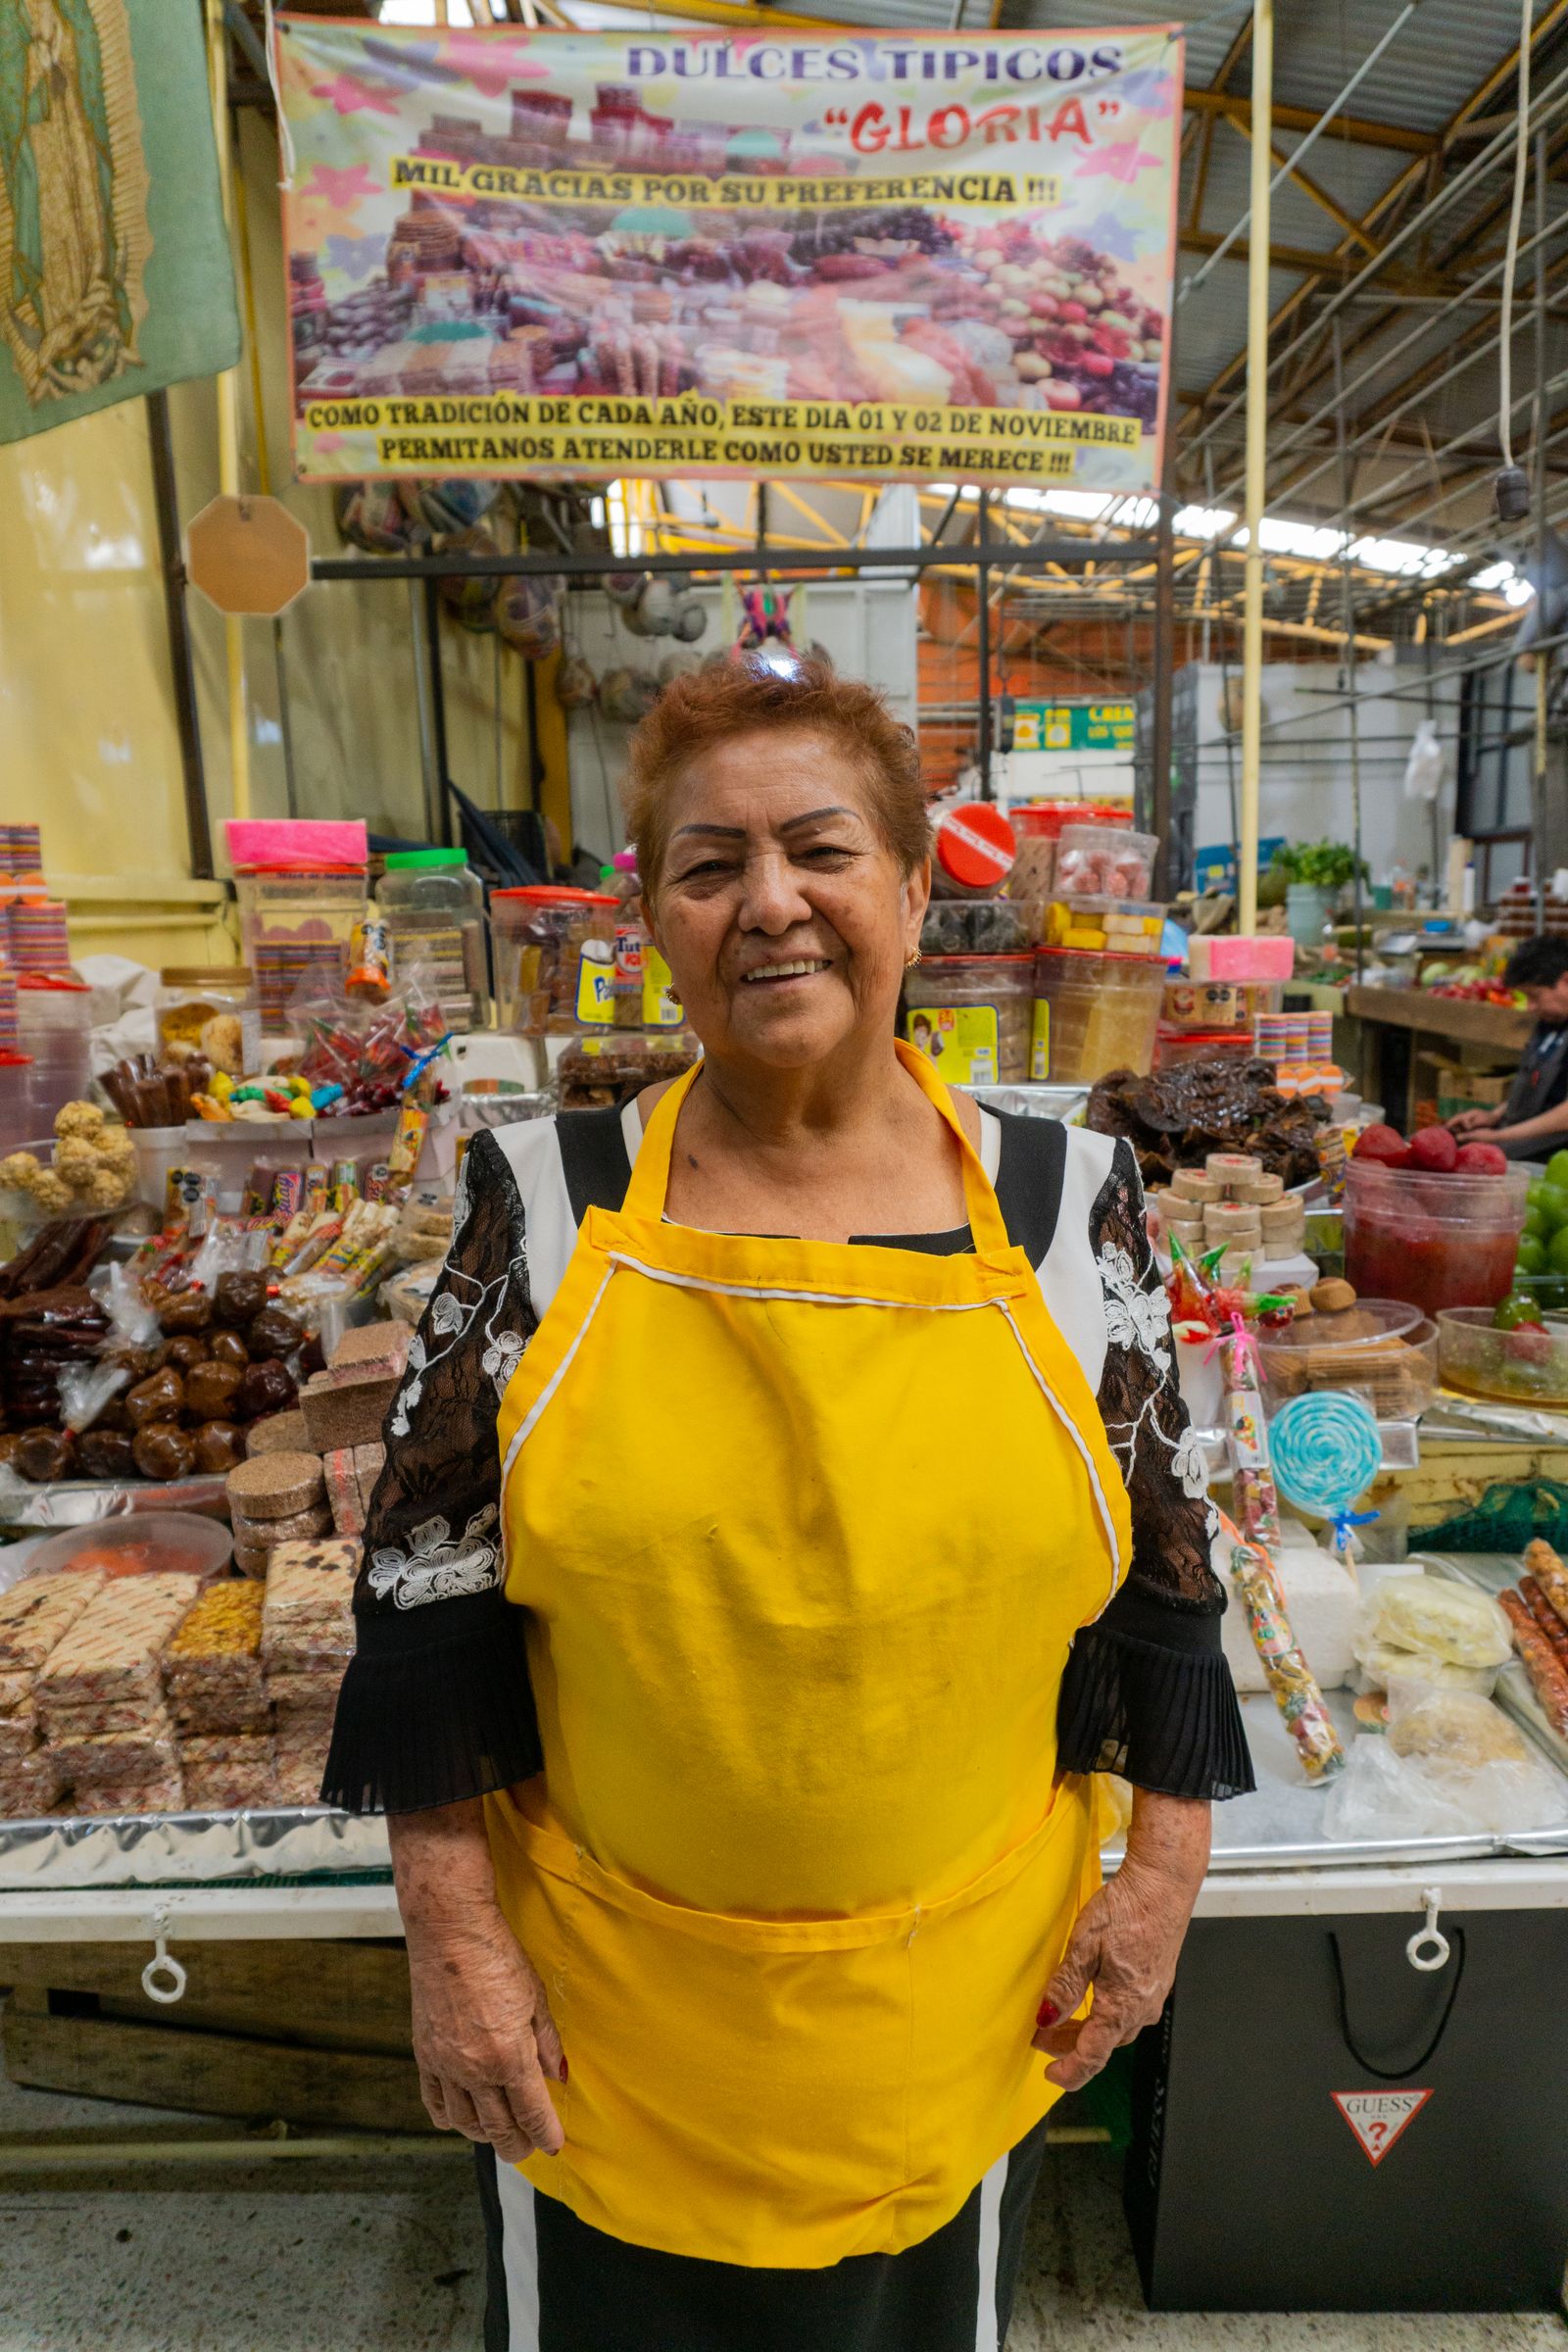 Market vendorsGeneral liability for weekend stalls
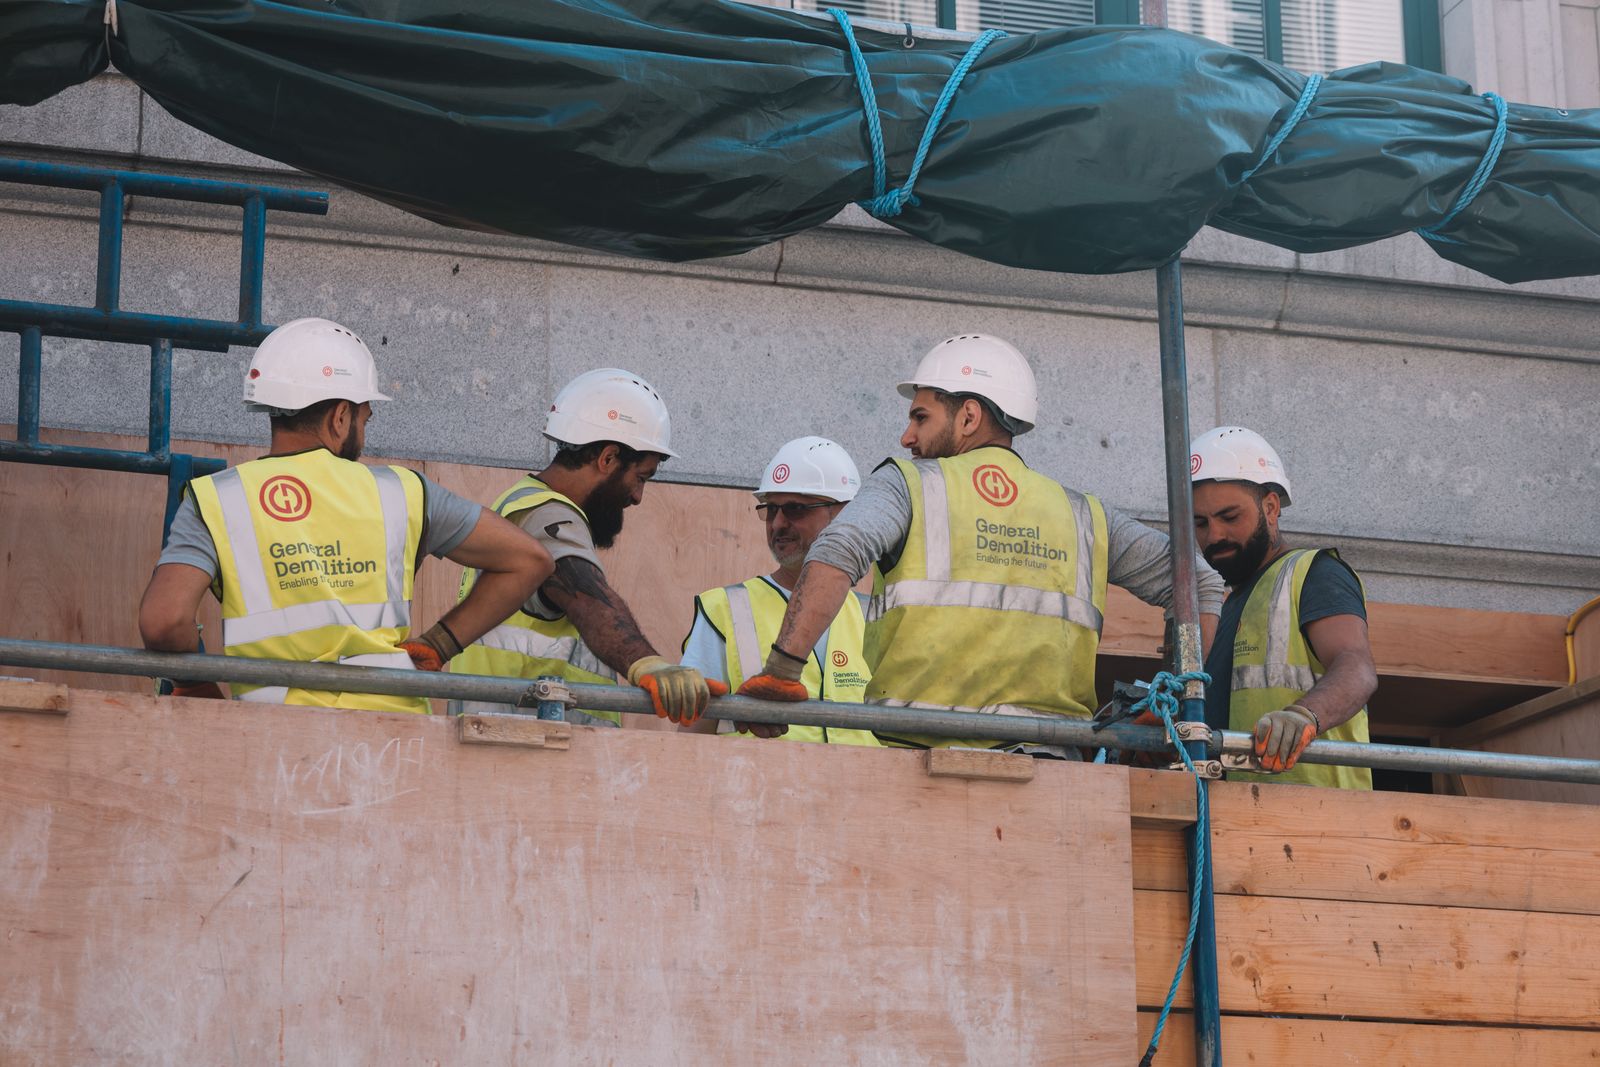 Framing and roofing crewsWorkers' comp and certificates
 First apartments near UTSARenters coverage for leases
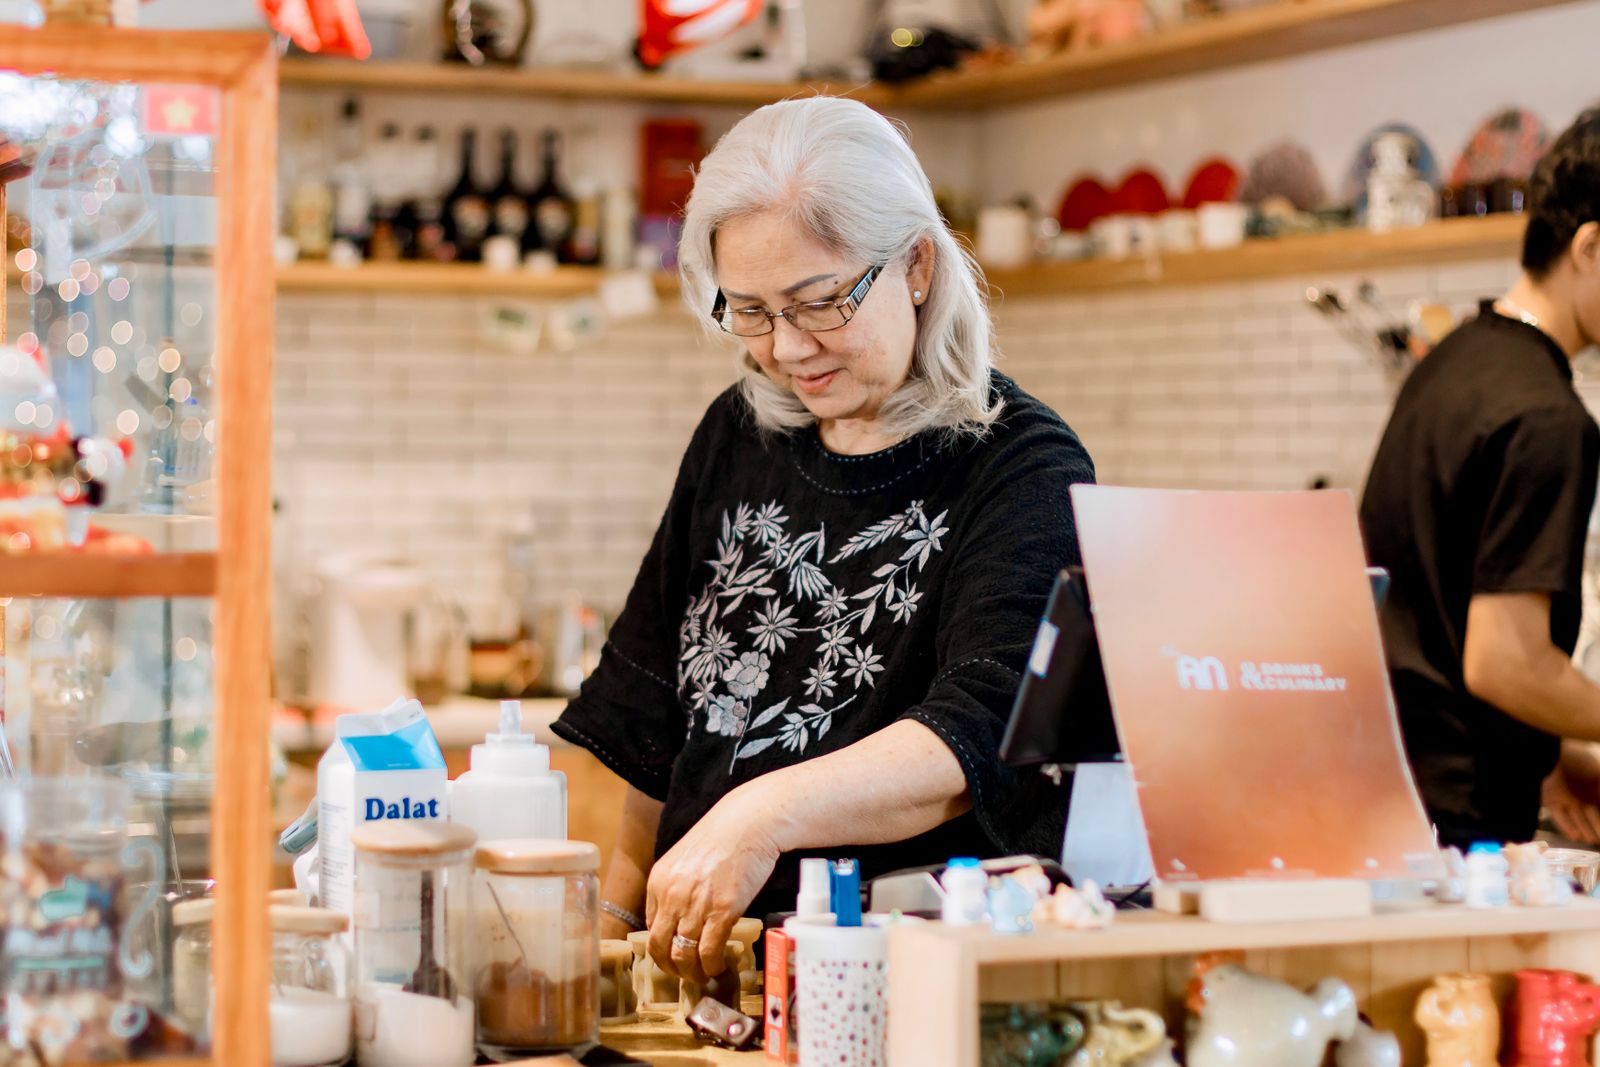 Neighborhood cafésBusiness owners policy with cyber
 Grandparents planning aheadFinal expense and whole life
 Cleaning and service vansCommercial auto for work vehicles
Pick a storm. We will show you what a typical policy pays for and the fine print our agents check first.
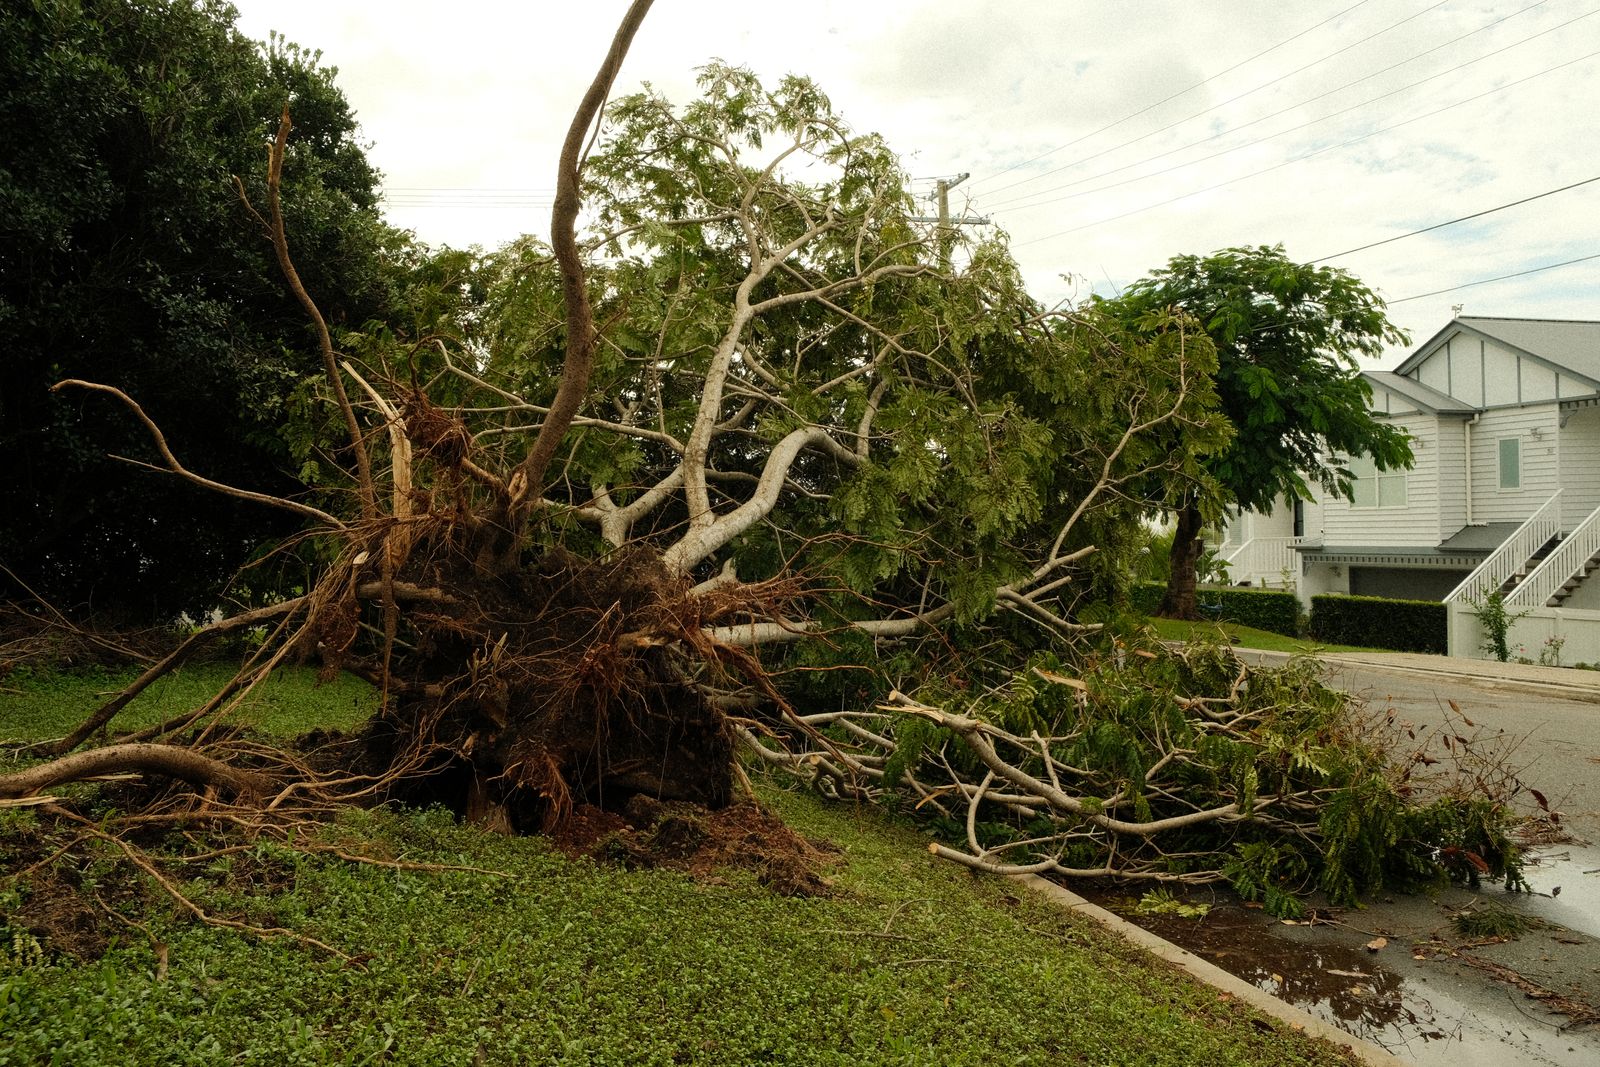
North Bexar and Comal counties see some of the most frequent hail in the country. Most damage is covered, but your roof deductible decides the check.
Usually covered
Our agents check
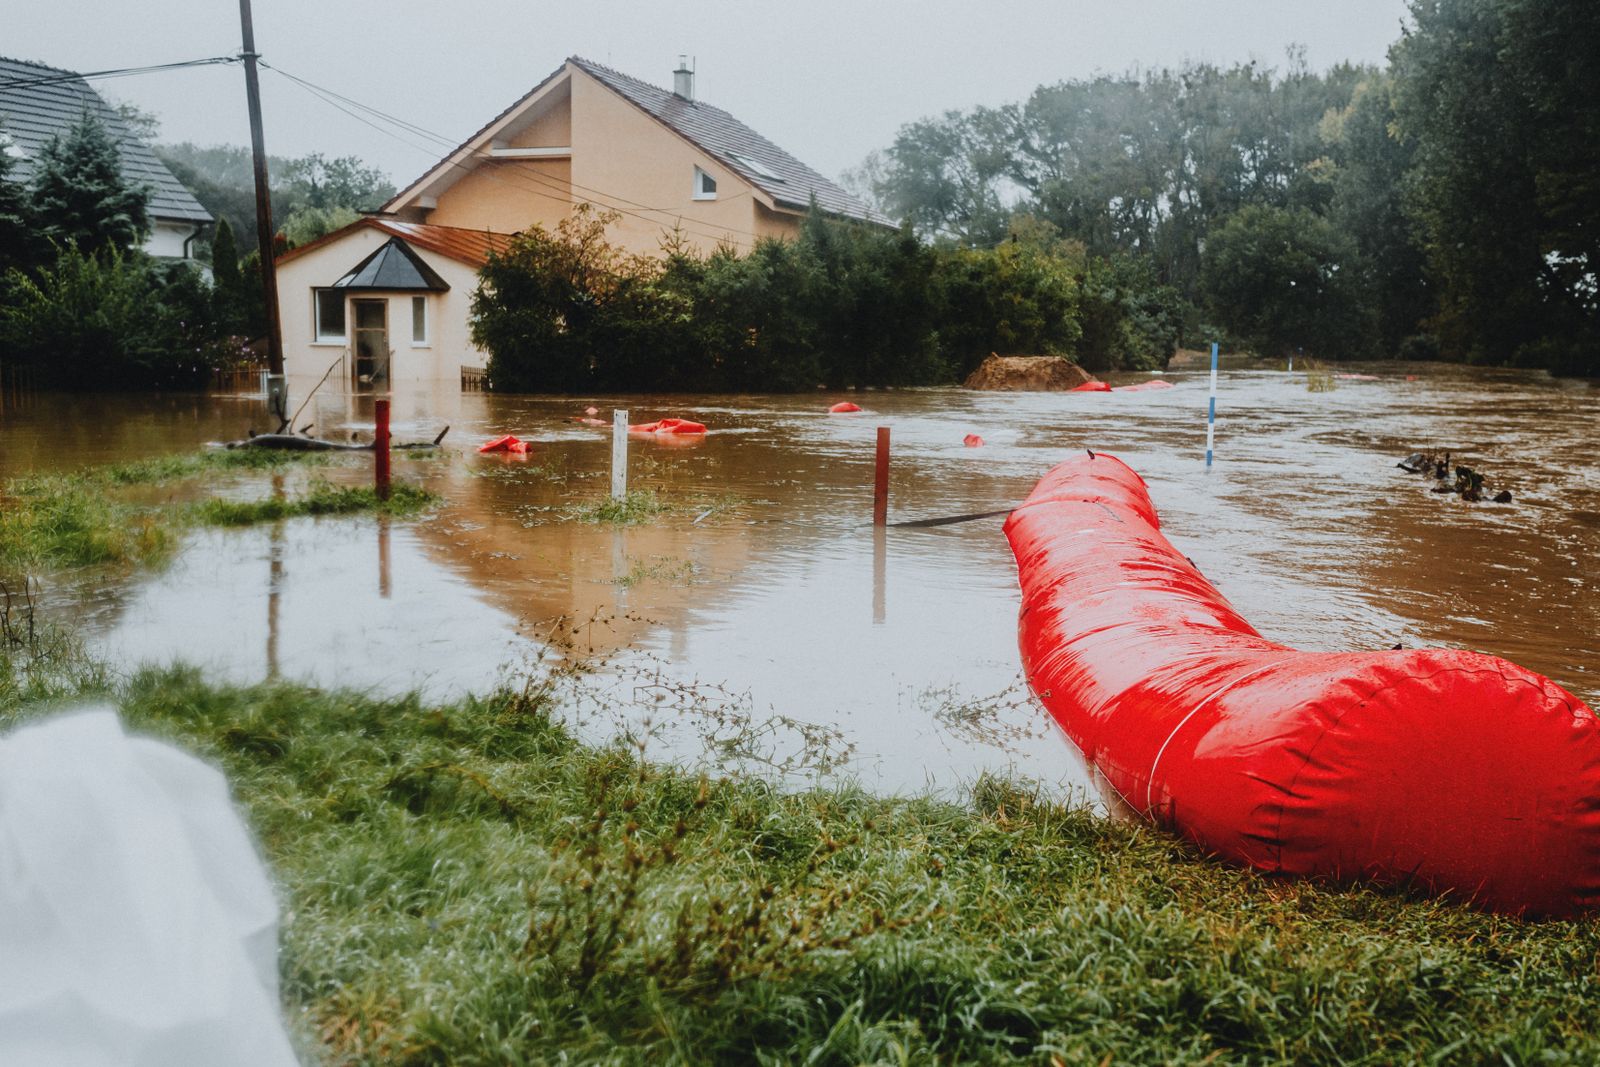
Hill Country rain moves fast down Salado, Leon and Cibolo creeks. Rising water is excluded from homeowners policies and needs its own flood policy.
Usually covered
Our agents check
The 2021 freeze taught Texas that pipes in attics and exterior walls are vulnerable. Sudden bursts are usually covered, slow leaks are not.
Usually covered
Our agents check
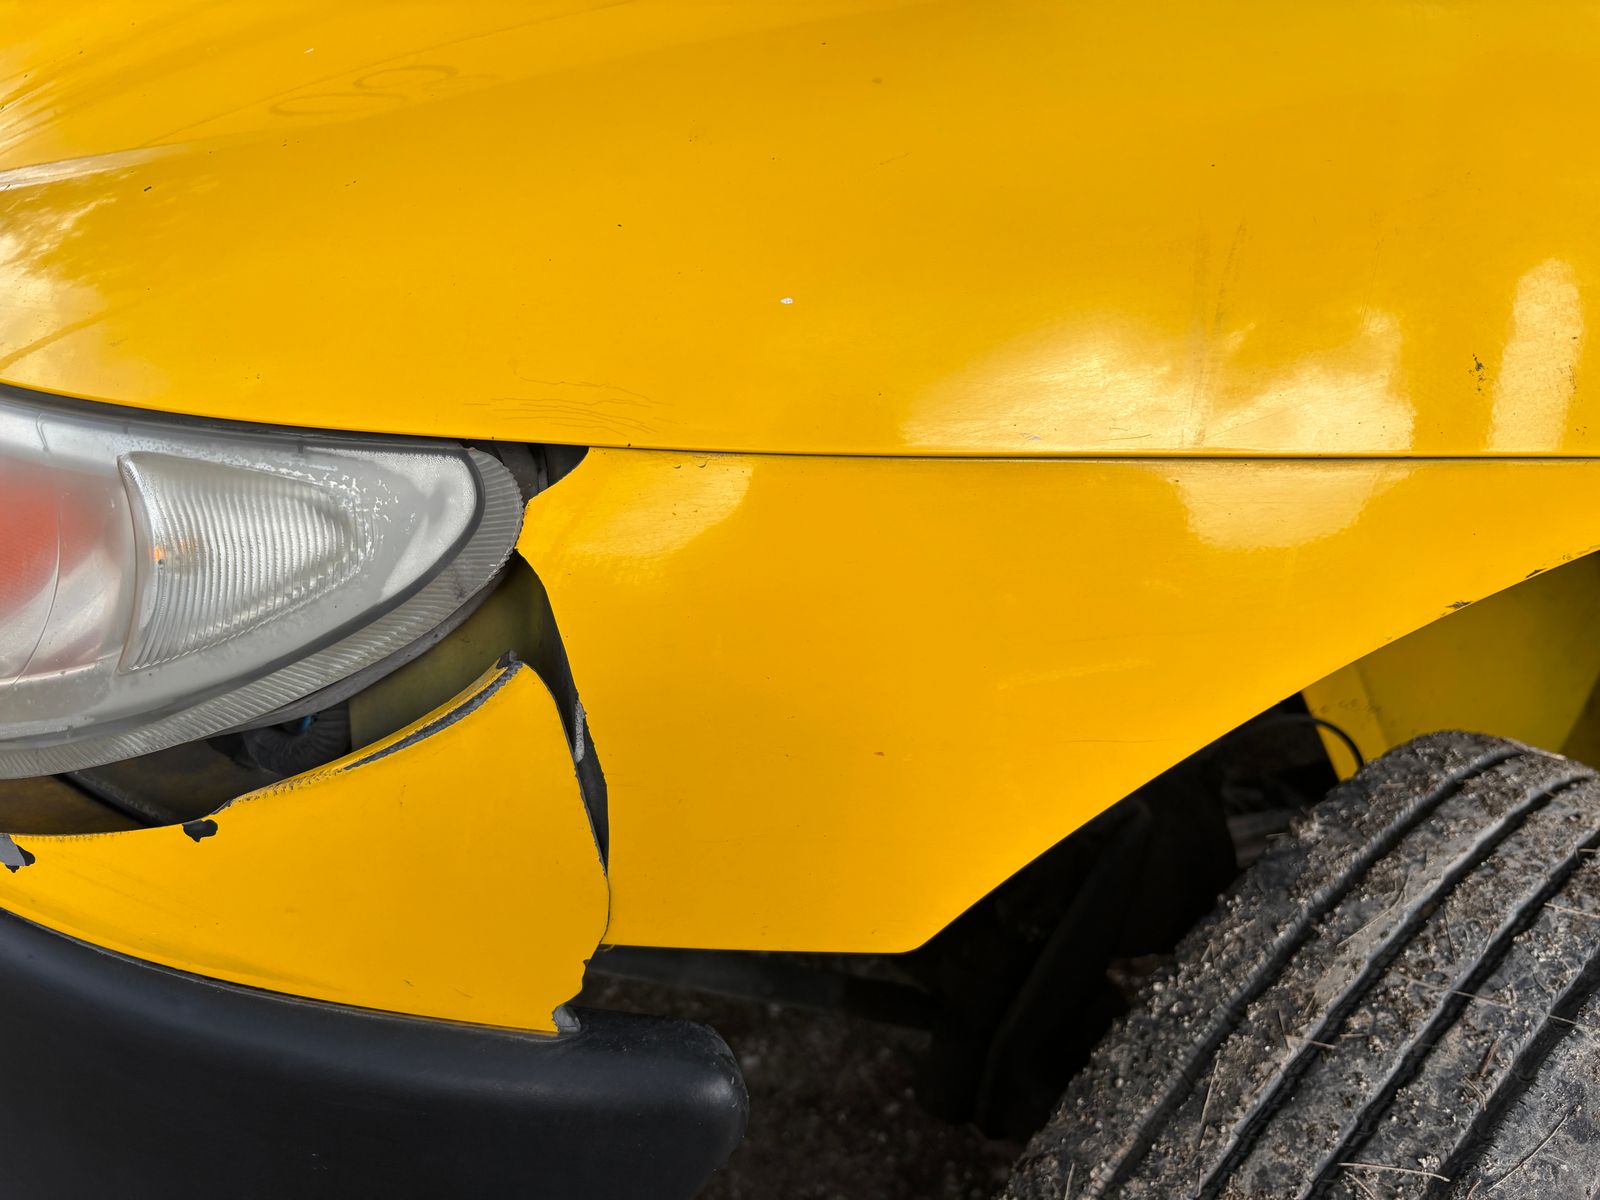
Hail dents, flooded interiors and fallen limbs are comprehensive claims. Liability-only policies pay nothing for your own car.
Usually covered
Our agents check
4.9
1,284 verified reviews (sample)
“After the April hailstorm, Daniela walked me through the claim and caught that my roof was paid at actual cash value. We fixed that at renewal. Real advice, not a sales pitch.”
“Adding our 16-year-old looked scary. They quoted three carriers and found a telematics discount that saved us about $60 a month.”
“Nos explicaron todo en español, sin prisa. Tenemos la panadería asegurada y el certificado para el arrendador llegó el mismo día.”
“Nobody had ever mentioned flood coverage for our place near the Comal. Sunbelt did, and two years later that policy mattered.”
“Two work trucks, four drivers and GC certificates every week. They answer texts fast and never make me chase paperwork.”
“Clear numbers, no pressure, and no medical exam. The whole application took one evening.”
“I needed an SR-22 after a rough year. No judgment, filed with DPS the same afternoon, and they are already helping me get back to standard rates.”
“Had coverage in place a week before closing and they sent everything to our lender. Wish the first quote had come a day sooner, but great follow-up.”
“Me ayudaron a entender la diferencia entre tener seguro de compensación o no. Ahora puedo trabajar con contratistas grandes.”
Carriers do not always apply them automatically. We ask the questions that unlock them.
Sample multi-policy savings when both policies sit with one carrier.
Estimate your bundleSample offer. Availability varies by carrier. Reviewed through Dec 31, 2026.
Class 4 shingles can cut the wind and hail portion of your home premium.
See roof creditsSample offer. Availability varies by carrier. Reviewed through Dec 31, 2026.
For teen drivers with a B average or a completed driver education course.
Auto discountsSample offer. Availability varies by carrier. Reviewed through Dec 31, 2026.
A 20-minute review of every policy you own, in English or Spanish.
Book a policy reviewSample offer. Availability varies by carrier. Reviewed through Dec 31, 2026.
“When the freeze burst our pipes, I called Sunbelt before I called the plumber. Ana stayed on the phone with me in Spanish, told me exactly what to photograph and had the adjuster at our house in two days. That is why my whole family insures with them now.”
Short, honest answers. For anything specific to your policy, an agent is one call away.
Still deciding? Talk it through with a licensed agent in English or Spanish.
We are not tied to one insurance company. We compare several carriers for the same coverage and help you choose, then stay your point of contact for changes, renewals and claims.
No. Carriers pay us a commission that is built into the premium you would pay anyway. You get comparison shopping and advice at no extra cost.
For emergencies, call 911 first, then your carrier's 24/7 claim line to open the claim. Then call us during business hours and we will follow up with the adjuster for you.
No. Flooding from rising water requires a separate flood policy, which usually has a 30-day waiting period.
An SR-22 is a certificate your insurer files with Texas DPS proving you carry at least minimum liability coverage. It is usually required for 2 years after certain violations.
Sí. La mitad de nuestro equipo habla español y puede atenderle por teléfono, WhatsApp o en nuestra oficina.
Real agents in San Antonio, answers in English or Spanish, and no obligation to switch.
4.9 average from 1,284 client reviews
We value your privacy
We use cookies to run this site, remember your preferences and understand how it is used.Cookie policy