Umbrella insurance in San Antonio
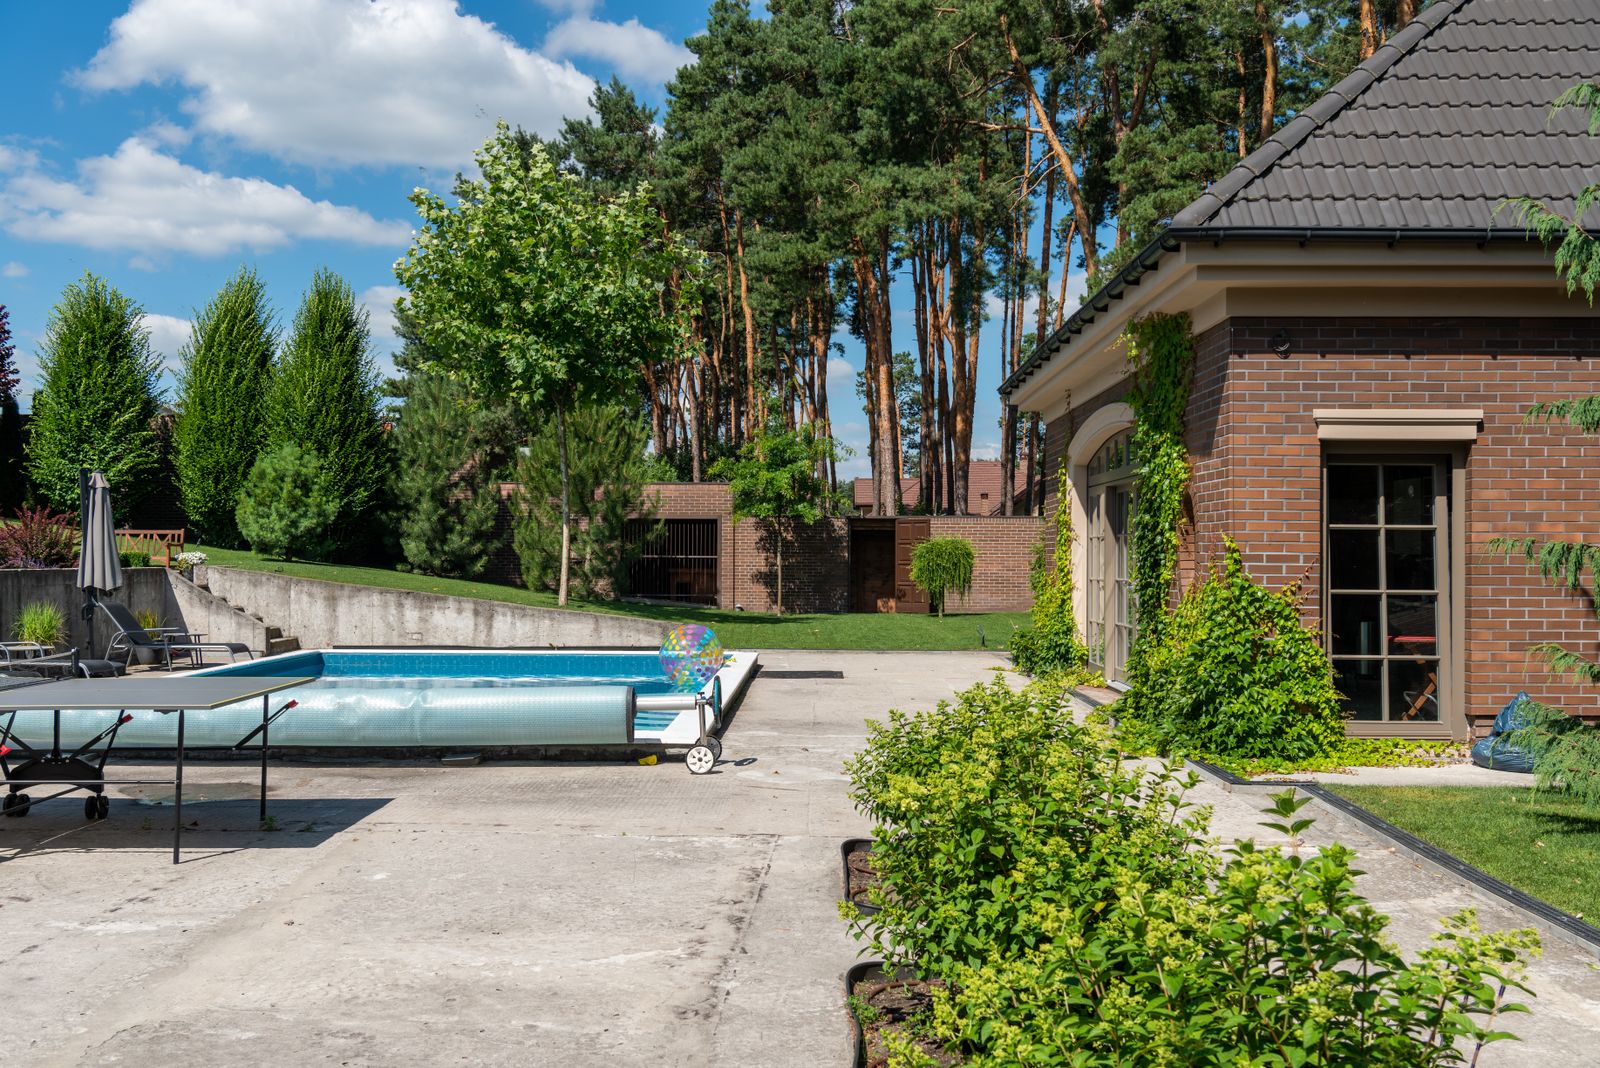
A pool, a teen driver or a rental property raises your liability risk. An umbrella adds $1 million or more above your other policies.
How we approach umbrella coverage
Serious injury lawsuits easily exceed the liability limits on a standard auto or home policy. A personal umbrella sits on top of those policies and pays once their limits are used up.
We make sure your underlying auto and home limits meet the umbrella carrier's requirements, so there is no gap between where one policy stops and the next starts.
- Protects future wages and savings
- Low cost per million
- Covers the whole household
- Easy to add to a bundle
What's included
Core protections and the options our agents most often recommend. Exact coverage depends on the carrier and your policy terms.
Excess auto liability
Serious crash injuries above your auto liability limit.
Excess home liability
Injuries on your property, including pool and trampoline accidents.
Personal injury
Claims of libel, slander and false arrest.
Legal defense costs
Attorney fees, often paid in addition to the limit.
Worldwide coverage
Liability that follows you when you travel.
Rental property liability
Extends over eligible landlord policies you own.
How getting covered works
- 1
Review underlying limits
We check auto and home liability requirements.
- 2
Choose the umbrella limit
$1M, $2M or more based on assets and risk.
- 3
Align renewal dates
Easier management when policies renew together.
- 4
Bind coverage
Often effective the same week.
What affects your price
Carriers weigh these factors differently, which is exactly why comparing several of them pays off.
- Drivers and vehicles
- Youthful drivers raise umbrella pricing.
- Properties
- Pools, rental homes and watercraft add exposure.
- Limit
- Each additional million costs less than the first.
- Underlying policies
- Bundling with the same carrier often lowers price.
Umbrella insurance questions
More answers on our FAQ page.
Anyone with a home, savings, a pool, teen drivers, rental property or a public-facing job. It is inexpensive protection for your future income.
No. Business liability requires a commercial umbrella or excess policy. We can quote that separately.
Many carriers require 250/500/100 auto liability and $300,000 home liability. We adjust your policies to match.
Often paired with umbrella
Auto insurance
Liability, full coverage, uninsured motorist and roadside help, shopped across 20+ carriers.
View coverage
Home insurance
Dwelling, belongings and liability, with roof, hail and wind deductibles explained plainly.
View coverage
Life insurance
Term, whole and final expense life insurance with plain-language needs analysis.
View coverageCompare umbrella quotes today
Real agents in San Antonio, answers in English or Spanish, and no obligation to switch.
4.9 average from 1,284 client reviews