Hail, flood and freeze: what your policy really pays
A plain-language guide to Texas weather claims, with sample deductible math and the exclusions we check first.
Texas weather, translated into plain coverage
Pick a storm. We will show you what a typical policy pays for and the fine print our agents check first.
Spring hail and straight-line wind
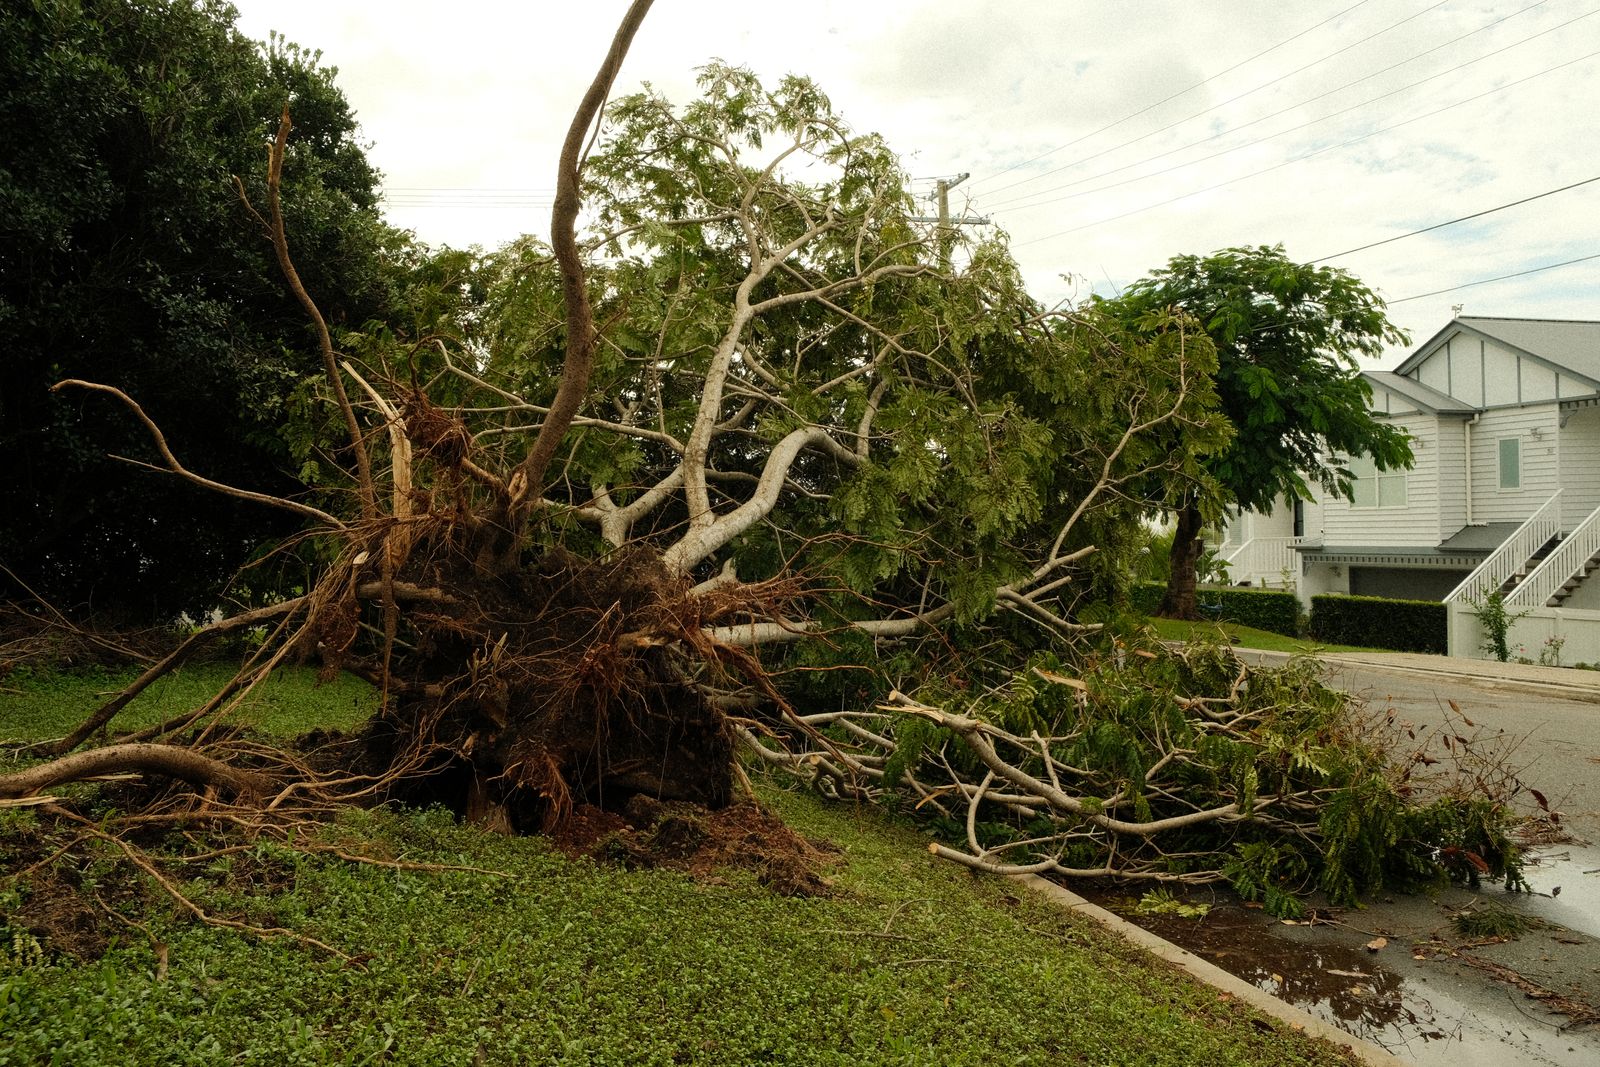
North Bexar and Comal counties see some of the most frequent hail in the country. Most damage is covered, but your roof deductible decides the check.
Usually covered
- Roof, siding and window damage
- Fallen trees that hit the house
- Hail on cars with comprehensive
Our agents check
- Percentage wind and hail deductibles
- Roofs paid at actual cash value
- Cosmetic metal roof exclusions
Flash flooding and rising water
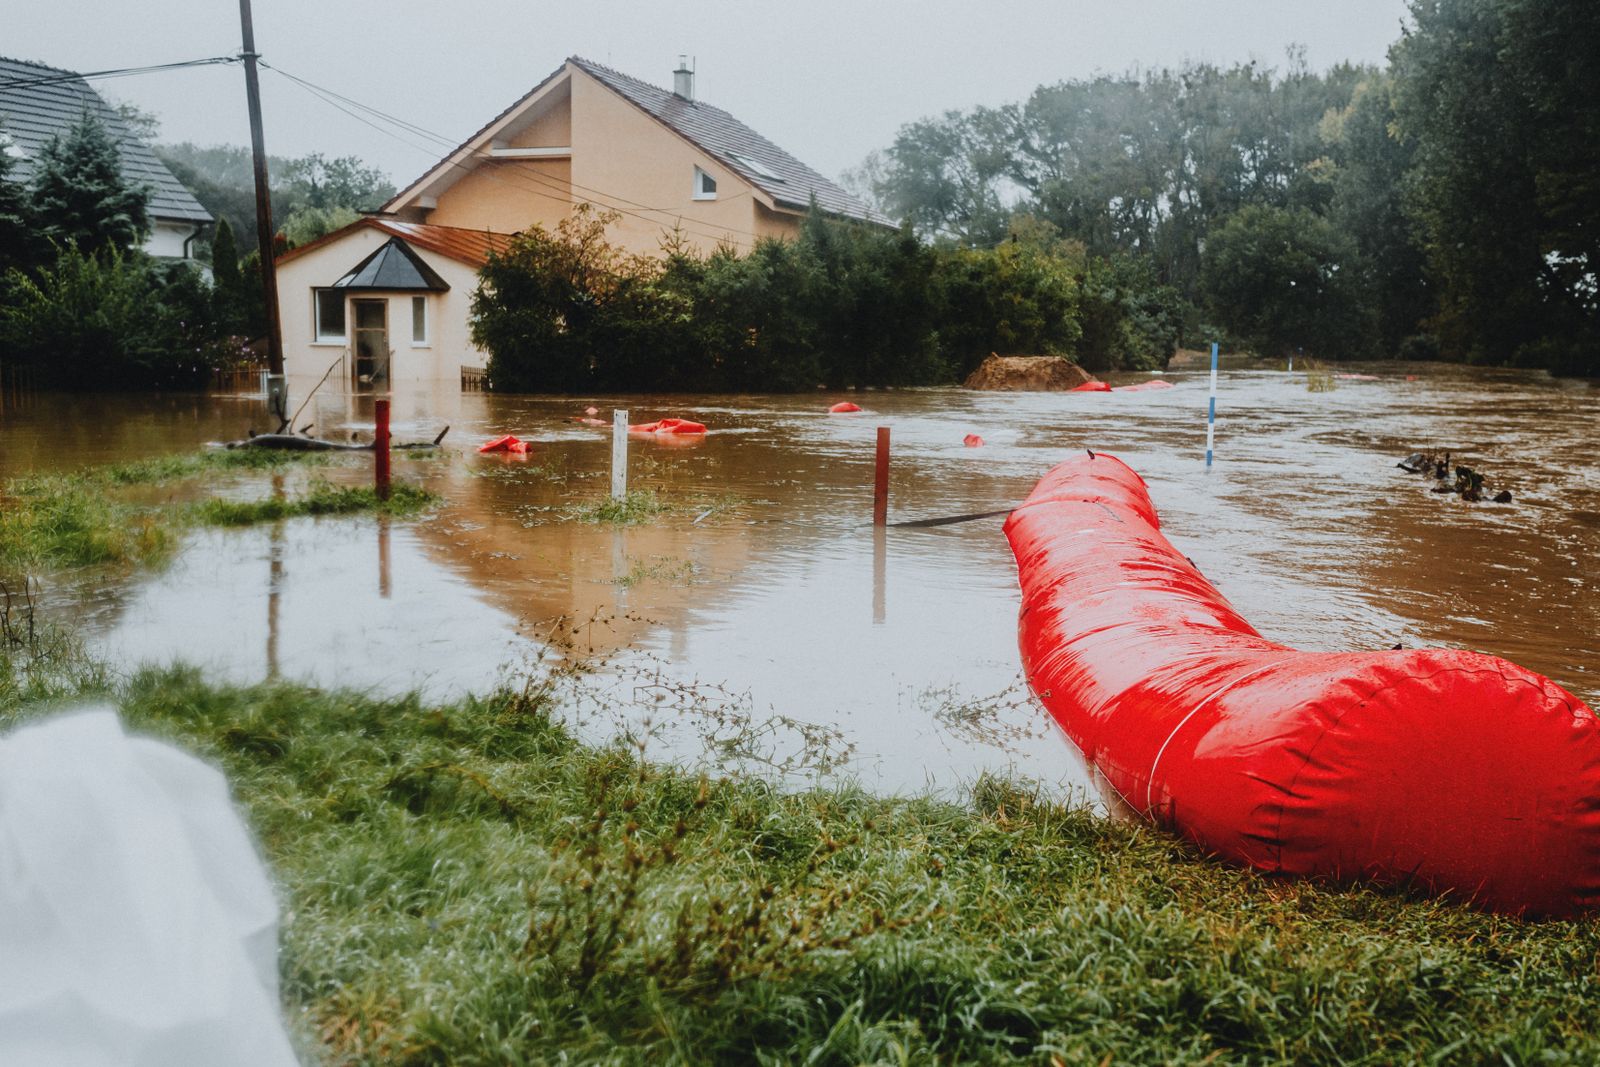
Hill Country rain moves fast down Salado, Leon and Cibolo creeks. Rising water is excluded from homeowners policies and needs its own flood policy.
Usually covered
- Flood policy: building up to $250K (NFIP)
- Contents coverage up to $100K
- Flooded cars with comprehensive
Our agents check
- 30-day waiting period on new flood policies
- Basement contents limits
- No coverage from homeowners alone
Freezes and burst pipes
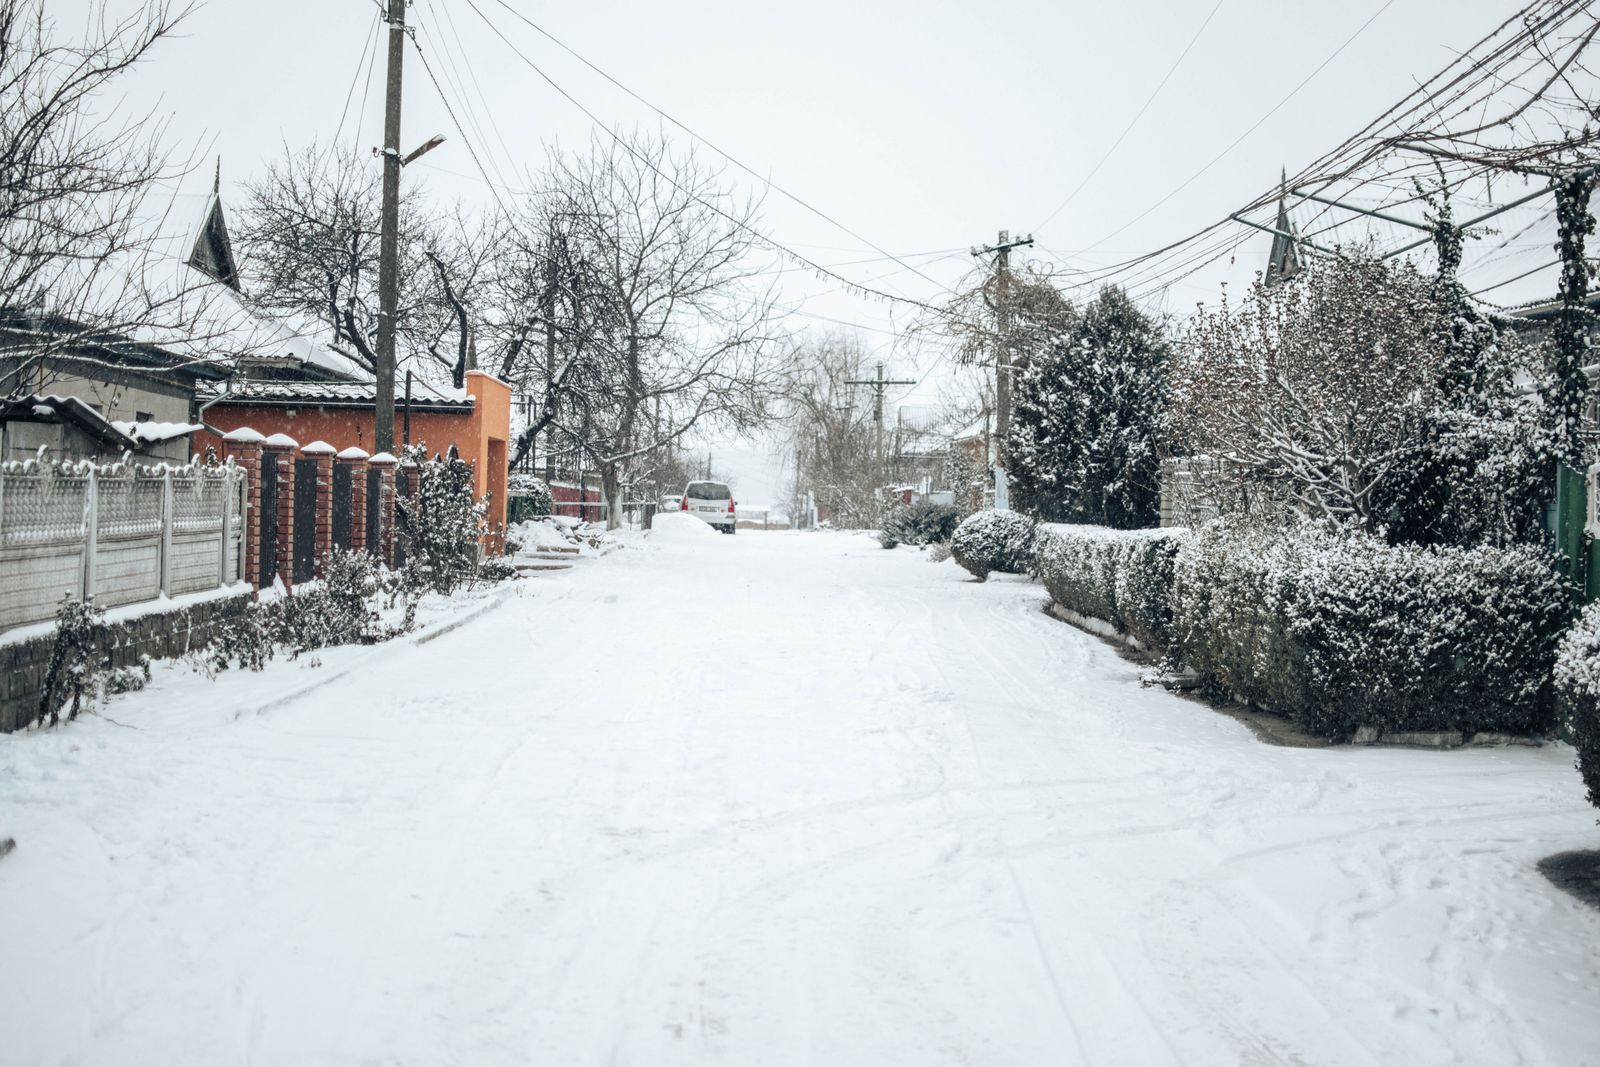
The 2021 freeze taught Texas that pipes in attics and exterior walls are vulnerable. Sudden bursts are usually covered, slow leaks are not.
Usually covered
- Sudden burst pipe water damage
- Hotel costs while repairs happen
- Spoiled food after power loss (some carriers)
Our agents check
- Damage while a home sits unheated
- Long-term leaks and mold limits
- Well pump and outdoor plumbing
Storm damage to your vehicles
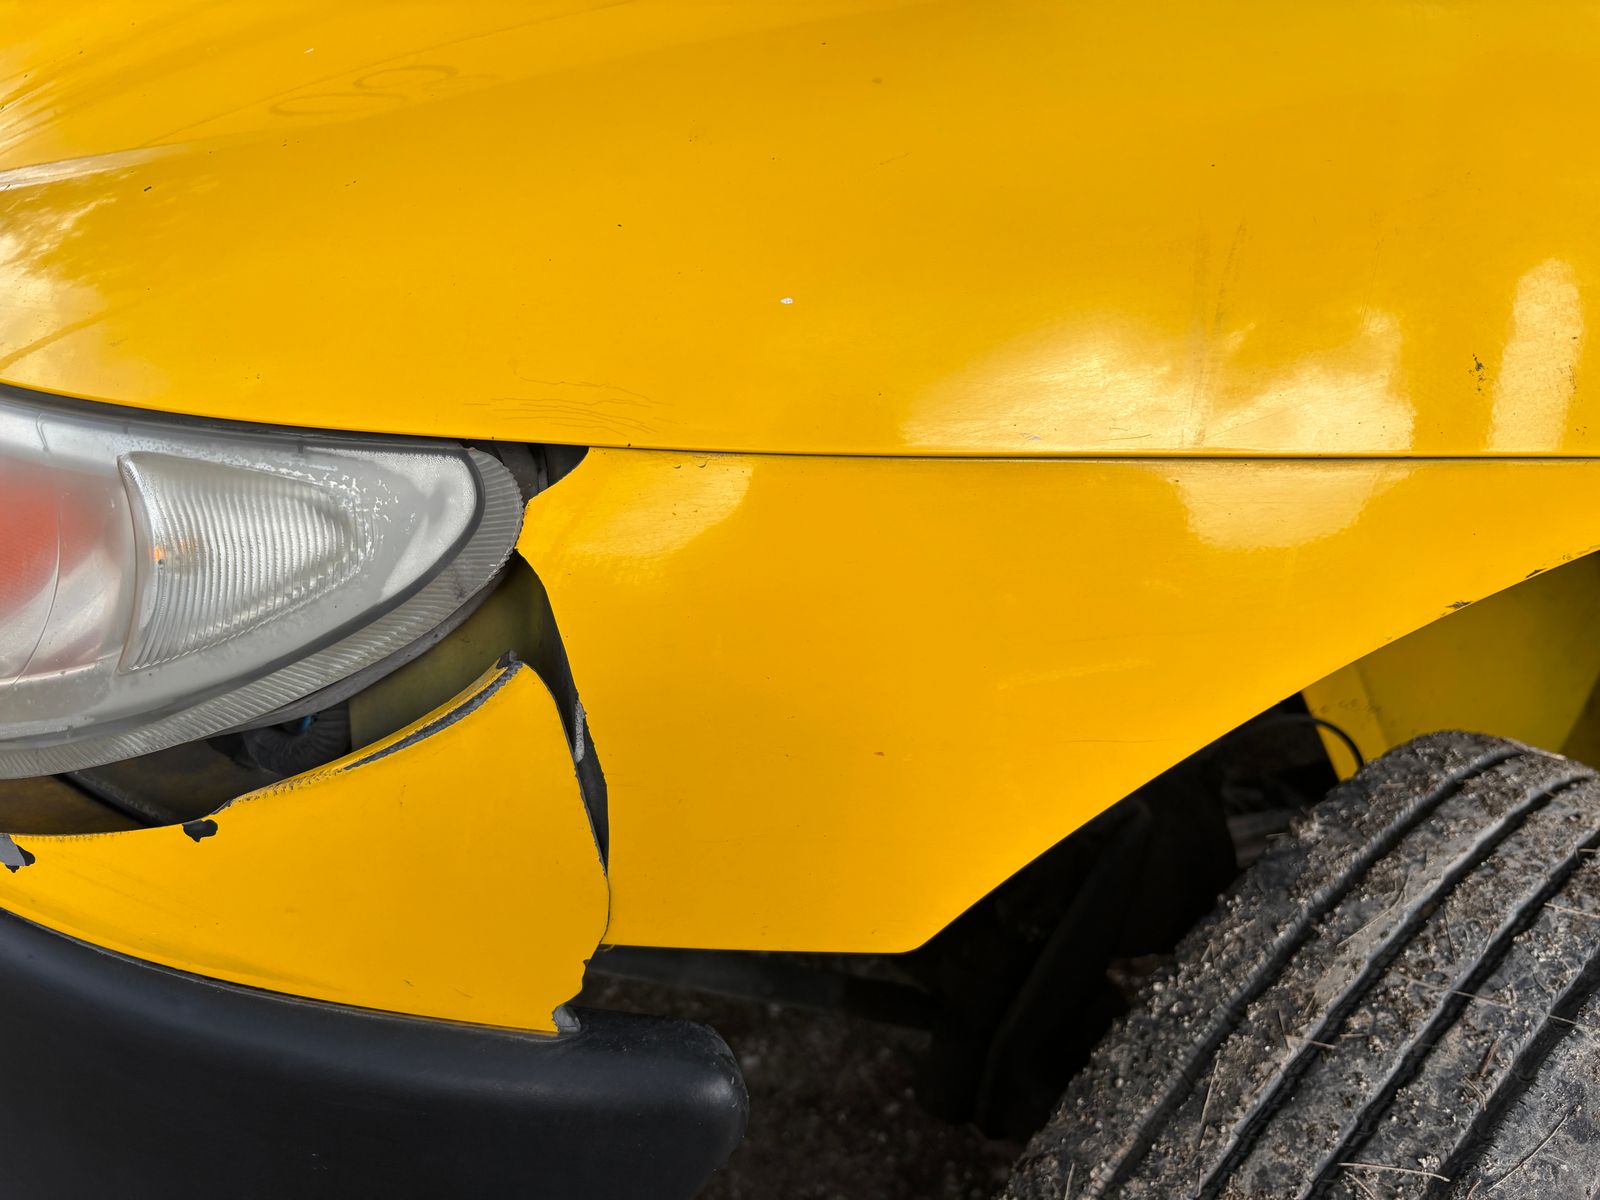
Hail dents, flooded interiors and fallen limbs are comprehensive claims. Liability-only policies pay nothing for your own car.
Usually covered
- Hail dents and broken glass
- Flood-damaged engines and interiors
- Rental car with rental reimbursement
Our agents check
- Liability-only policies
- High comprehensive deductibles
- Aftermarket parts limits
Which policy pays for which storm
Typical outcomes. Your policy wording, endorsements and exclusions control every claim.
| What happened | Homeowners | Flood policy | Auto comprehensive |
|---|---|---|---|
| Hail damages your roof | Yes, after wind and hail deductible | No | Not applicable |
| Creek overflows into your living room | No (flood exclusion) | Yes, after 30-day wait | Not applicable |
| Wind-driven rain through a storm-damaged roof | Usually yes | No | Not applicable |
| Car floods in a low-water crossing | No | No | Yes, with comprehensive |
| Pipe bursts during a freeze | Usually yes (sudden and accidental) | No | Not applicable |
| Sewer backs up into the house | Only with water backup endorsement | Only if caused by a flood | Not applicable |
Percentage deductibles in real dollars
Many Texas home policies use a wind and hail deductible based on your dwelling limit, not a flat amount.
| Dwelling limit | 1% deductible | 2% deductible |
|---|---|---|
| $250,000 | $2,500 | $5,000 |
| $350,000 | $3,500 | $7,000 |
| $500,000 | $5,000 | $10,000 |
Sample math for illustration.
Read: how to read your roof deductible
Before storm season checklist
- 01Photograph your roof, gutters and home exterior every spring
- 02Keep roof installation receipts and Class 4 certificates
- 03Check your flood zone and buy flood coverage 30+ days before storm season
- 04Store your carrier's claim number and policy number in your phone
- 05Know which low-water crossings to avoid on your commute
- 06Insulate exposed pipes and know where your main water shutoff is
Weather coverage questions
No. Flooding from rising water requires a separate flood policy, which usually has a 30-day waiting period.
Many carriers offer discounts for Class 4 impact-resistant shingles. Keep your installation certificate and send it to us.
It is happening more often in Texas. Call us as soon as you get the notice and we will shop replacement coverage before the policy ends.
Check your roof and flood coverage
Real agents in San Antonio, answers in English or Spanish, and no obligation to switch.
4.9 average from 1,284 client reviews